Mastercard’s stablecoin bet: check before paying
The October 19, 2026 announcement puts risk checks before the transfer. What Stablecoin Security promises and what still needs evidence.
On this page
Before making a payment faster, should it be allowed to leave? On October 19, 2026, Mastercard announced Stablecoin Security, a risk assessment service with Borderless.xyz and Keyrails as its initial partners. The launch starts in North America; worldwide commercial availability is expected in 2027.
That step matters to people using digital payments. A technically valid transaction can still reflect a bad decision: an altered invoice, a misidentified recipient or a request the sender did not understand. Faster execution does not resolve any of those questions.
The decision comes before confirmation
A stablecoin aims to track a reference asset, often a currency. That property does not tell you who should receive the money. It does not establish that a purchase will arrive or that a refund will be accepted.
Imagine a rental invoice sent to a group of friends with altered payment details. This is a hypothetical example, not a reported incident. The group might calculate every share correctly and still pay the wrong recipient. Working out the amount, verifying the request and executing the payment are separate tasks.
Growth figures need a denominator
On October 1, Visa reported that roughly 17% of its stablecoin-linked card volume came from business and commercial programs in fiscal 2026 to date. This uses internal VisaNet classifications. It is neither 17% of all payments nor a measure of friends paying one another back.
Our interpretation: a business-card indicator warrants attention to company payment needs, without demonstrating everyday consumer adoption. Financial volume does not count people. A conclusion about use requires knowing the population, period and transactions included.
A risk signal is not a guarantee
A check helps someone make a decision; the outcome for the customer remains another question. To evaluate a service, we would look for error rates, legitimate payments delayed and the process for challenging a decision. Without those measures, an announcement describes a proposed capability rather than observed effectiveness.
Another example of that separation appears on the Visa Stablecoin Platform page. It describes two-person approval for certain operations, while stating limited availability and beta Open USD access with geographic and volume limits. A control listed in a product catalogue is not necessarily available in every payment app.
What to examine in your own payment flow
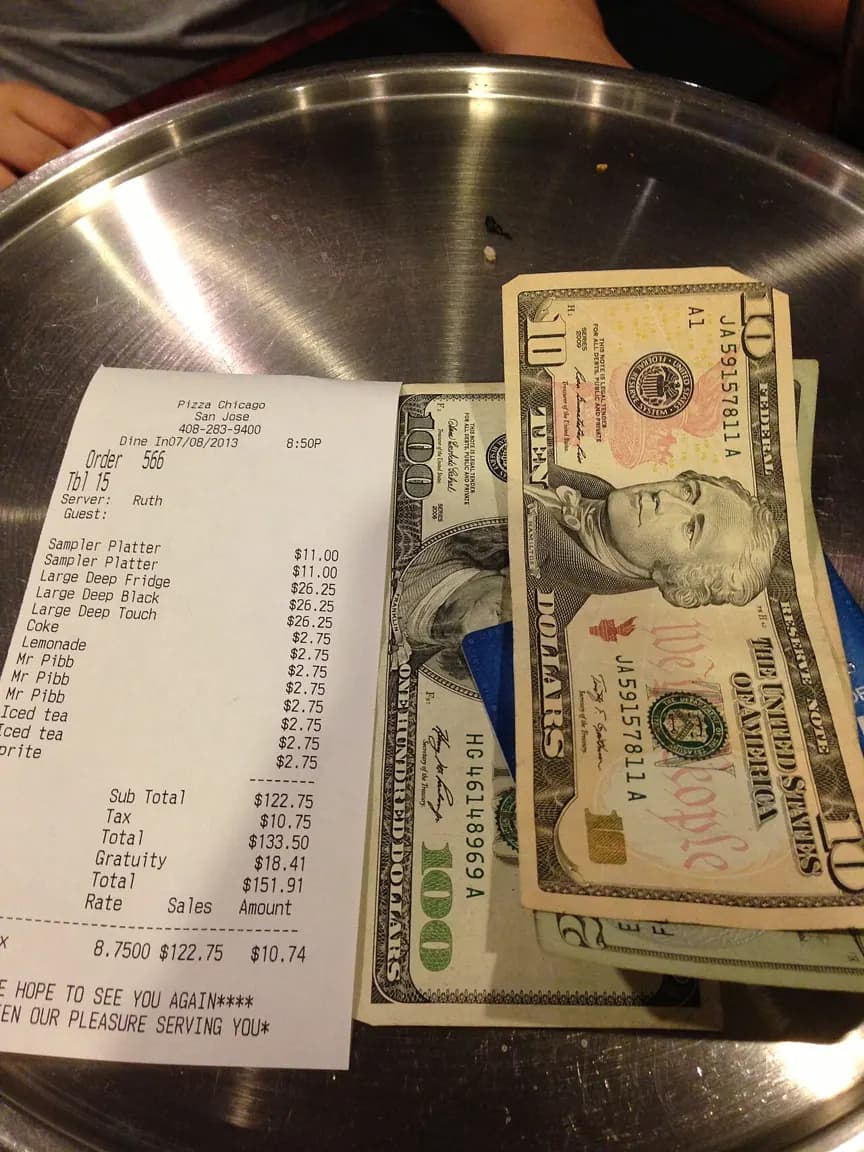
For someone repaying an expense, useful questions concern the confirmation screen and the receipt:
- Is this the intended recipient, and how was that checked?
- What amount will arrive, in which currency, after any fees?
- Who can respond if the payment stays pending or the request was fraudulent?
These questions let people compare payment flows without treating a network’s name as a general guarantee. They also matter to shared-expense apps: showing a debt, recording a repayment and confirming receipt of funds describe different facts. In the current version of Spliz, members repay outside the app and then record it.
The test for this news is measurable: can services stop more suspicious requests while letting legitimate payments through? Transfer speed cannot answer that. Results and the options available to the person paying will matter more than the launch announcement.
Sources
- Mastercard, October 19, 2026 Stablecoin Security announcement and stated availability.
- Visa, October 1, 2026 VisaNet data on stablecoin-linked cards.
- Visa Stablecoin Platform, access conditions and approval controls.
Sources checked October 24, 2026. The analysis and hypothetical example are original; the announcements are not independent evidence of effectiveness.
Friends first. Enjoy the good times.