What Is Money? The Story of Who Keeps the Ledger
Your bank balance is a promise written in a ledger. Where it comes from, how banks create it, and who can freeze or rewrite it.
On this page
For centuries, from southern China to the Gulf of Guinea, millions of people paid with shells that came from a single archipelago. They bought rice, gold, and human beings with them. Then merchants from Hamburg found them somewhere else, and that money collapsed. Your paycheck is not a shell, but it raises the same question: who keeps the count, and who can touch it?
The story reads on its own. The “Go deeper” boxes add the technical detail and stay closed until you open one.
Prologue. On payday
On payday, nothing moves. Nobody crosses town with a sack. In a bank’s computer, a number next to your name gets bigger. You will trade it for rent, groceries, a train ticket, and everyone who accepts it will do so without knowing you.
To understand money, you can start from an image: a memory of exchanges, among people who cannot remember it all.
It lets you trade, measure prices and hold value for later. It’s only as good as people’s trust in it, and that trust has often been guaranteed by force. It works like the blood in a body: when it gets sick, nothing moves anymore.
That number on your screen is worth nothing in itself. It is worth something because millions of people believe it will still be worth something tomorrow, and because an institution keeps the ledger where it is written. Much of the history of money comes down to three questions about that ledger.
Who keeps it? Who can rewrite it? And who can erase you from it?
The fifteen stories that follow answer them, from a lagoon in the Indian Ocean to your banking app. By the end, you will know where the number in your account comes from, who can block it, and what really protects it.
These questions are not new. Before banks, much of the world paid with an object nobody wrote down anywhere: a small white shell. Its story shows what happens when someone else controls the source.
What happens when others make your money?
- The Maldives, 14th century: the shell that paid the world
- Hamburg, 1844: merchants flood the cowrie market
The Maldives, 14th century: the shell that paid the world
How did a shell become a global currency?
In the middle of the fourteenth century, the Moroccan traveler Ibn Battuta landed in the Maldives. He stayed a year and a half, serving as a judge. The islanders paid with small white shells, and the crown kept hoards of them. They also traded them for rice from Bengal, where the shells served as money, and Yemeni merchants loaded them into their holds in place of sand. About a decade later, in Mali, at Gao on the Niger River, Ibn Battuta found the same shells again: 1,150 to a gold dinar.
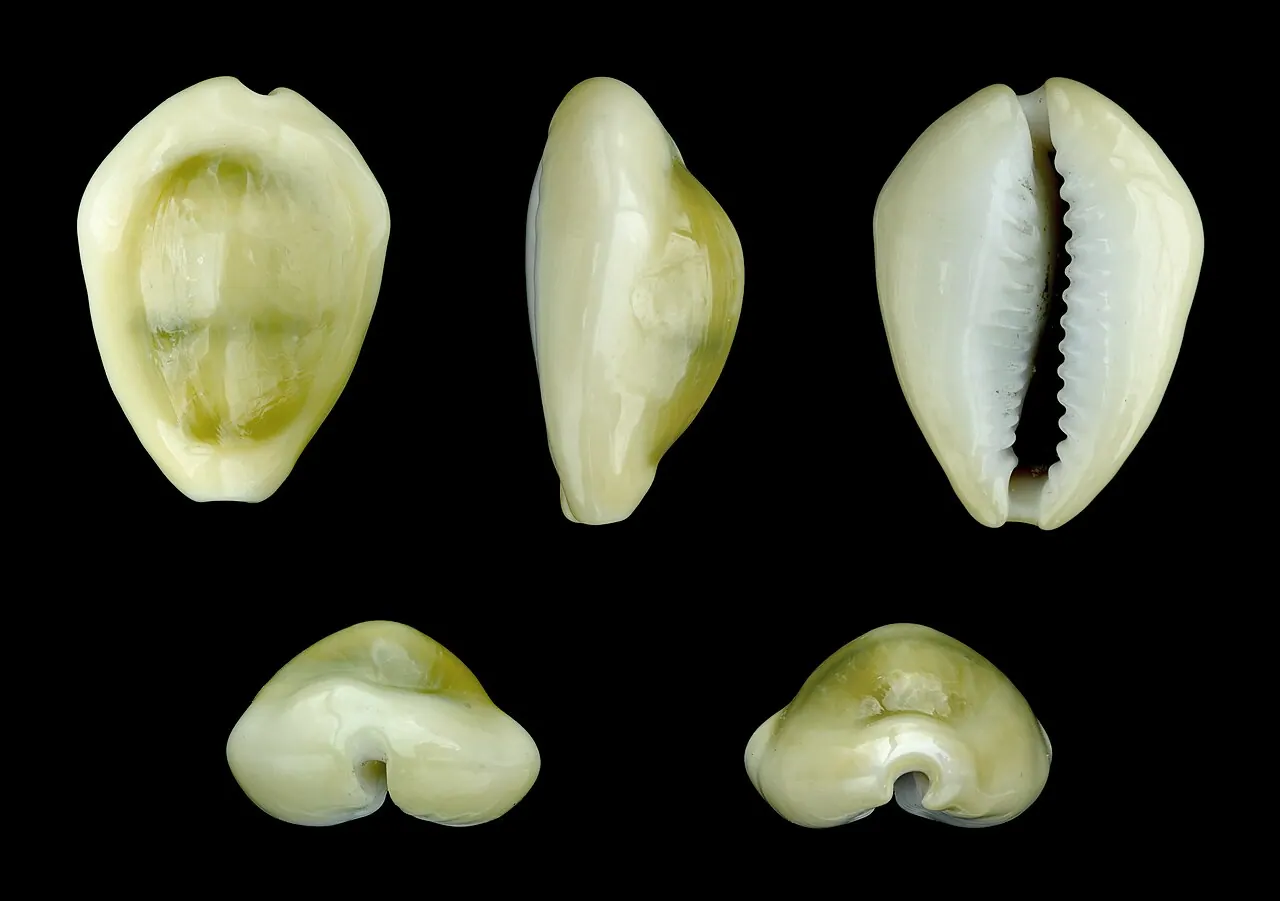
The shell is called a CowrieMonetaria moneta, a small sea snail of the Indian Ocean. The most prized came from the central atolls of the Maldives.Read on Wikipedia. It is durable, light, easy to count and nearly impossible to fake. And it comes from almost nowhere else. Three centuries after Ibn Battuta, the Frenchman François Pyrard, shipwrecked on the islands, still watched women wade into the lagoon up to their waists to pry the shells off the rocks, twice a month. The shells were then buried in the sand, sometimes for months, until the animal inside rotted away, and counted into bundles of 12,000 tied up in coconut leaves.
In Yunnan, in southern China, cowries were one of the main currencies for nearly a millennium, until the seventeenth century. The historian Bin Yang calls them “the first global currency”. No king made them. The sultan of the Maldives controlled their trade, but not their nature: nobody could produce many more.
In the sixteenth century the Portuguese entered this trade, followed by the Dutch, the English and the French. Their ships carried cowries to Europe as ballast, then shipped them on to the Gulf of Guinea. There they traded them for ivory, provisions and human beings, with African kings and merchants who set the terms of the sale.
In the seventeenth century the Dutch geographer Olfert Dapper reported that a third of the value of a captive had to be paid in cowries. London’s Royal African Company called them “almost a sine qua non” of the trade. At Ouidah, a port the kingdom of Dahomey conquered in 1727, figures compiled by Gildas Salaün of the Musée Dobrée in Nantes give the price of a person: 8,000 cowries in 1724, 80,000 in 1748, 192,000 in 1773. In June 1789 the Saturne sailed from Nantes for Guinea with nearly 35 metric tons of shells in its hold.
× 24the rise in the price of a person in cowries at Ouidah, from 1724 to 1773.
The price rose twenty-fourfold in half a century. Two forces drove it: soaring demand for captives, and the mass of shells poured onto the coast, which made each one worth less. The historian Toby Green sees a trap in this: paid in a currency that kept losing value, the kingdoms of West Africa gradually lost leverage against their European partners. Still, as long as the shells came only from the Maldives, their number had a limit. In the nineteenth century, that limit gave way.
Hamburg, 1844: merchants flood the cowrie market
What happens to money when the market is flooded?
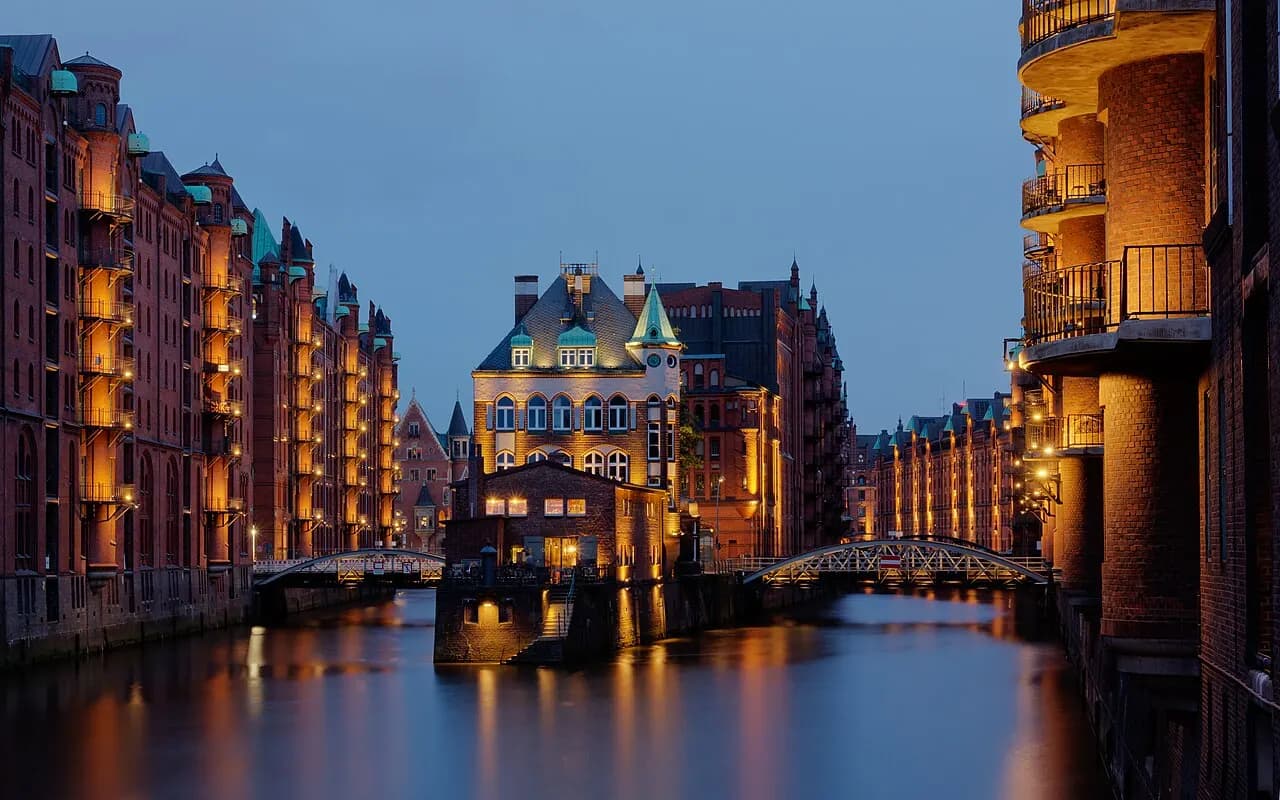
In 1844, in Hamburg, the trading house Hertz looked into the cowrie market. No European buyer had visited the Maldives “in living memory”: the British bought in Bengal. Britain had banned its subjects from the slave trade in 1807, others had kept it going, and the palm oil trade had revived demand for shells: since the 1830s, West Africa was again importing 90 to 135 metric tons of them every year.
The ship Hertz sent to the Maldives came back empty: the islanders refused to interrupt their rice trade. Hertz found another source in Zanzibar, on Africa’s east coast: a related cowrie, the Ring cowrieMonetaria annulus, a cowrie from the East African coast, slightly larger than the Maldivian one.Read on Wikipedia, which could pass for the other and cost far less. Hertz led the way; another Hamburg house, O’Swald, took over, and then the French firm of Victor Régis.
For the West African coast, it was as if someone had found a money printing press at the other end of the continent. The economic historian Jan Hogendorn sums up what followed in a single line: the market was flooded, and “a great inflation ensued”.
It took more and more shells to buy the same thing. As Leigh Gardner, a specialist in African economic history, explains, the cowrie became expensive to use: it had to be carried, counted and stored. Anyone who had saved in cowries watched those savings melt. The margins went to the Hamburg and French houses that imported the shell. Imagine your paycheck paid in a currency someone else can make at will.
Then the colonial administrations stepped in. From 1880 on, they imposed their own money and gradually banned the shell: in Lagos, only British silver coin was Legal tenderThe money the law requires people to accept as payment.Read on Wikipedia, and in southern Nigeria, importing cowries soon meant prison.
The shell held on. The courts of Buganda kept collecting fines in cowries for years, and in the Volta region, the anthropologist Mahir Şaul has shown, it took decades to wipe it out.
Bans were not enough. What replaced the cowrie was first its own inflation, then taxes and wages. A government that demands taxes in its own money forces everyone to get some. And when it pays its soldiers and railway workers in that same money, the money spreads all the way into the markets.
People sometimes say Europe paid for captives with shells. The mechanism was more precise than that. On the coast, African kings and merchants controlled the ports, the roads and the markets. None of them controlled the lagoon the shells came from. Those who held the source could make as many as they liked, and then those who held the guns decided which money would count.
Another story, from the Pacific, shows that scarcity is not enough either. On the island of Yap, the most valuable money was large stone disks, RaiLimestone disks quarried on the Palau islands and carried by canoe to Yap.Read on Wikipedia, cut by hand on the Palau islands and brought back by canoe. In the nineteenth century an Irish-American captain, David O’Keefe, had stones cut with iron tools and shipped them back by steamer. His stones were larger and better finished. They were worth less than the old ones, because they “weren’t authorized by any chief, were far less labour-intensive to make and gained no history”, as the Bank of Canada Museum puts it. A money holds through scarcity, and also through its users’ agreement on who has the right to create it. That right, long before cowries, accountants were already recording in clay.
Who wrote the first debt?
- Uruk, 5,000 years ago: the first writings were debts
- Lydia, 7th century BC: a coin, a signature
Uruk, 5,000 years ago: the first writings were debts
Did money come from barter?
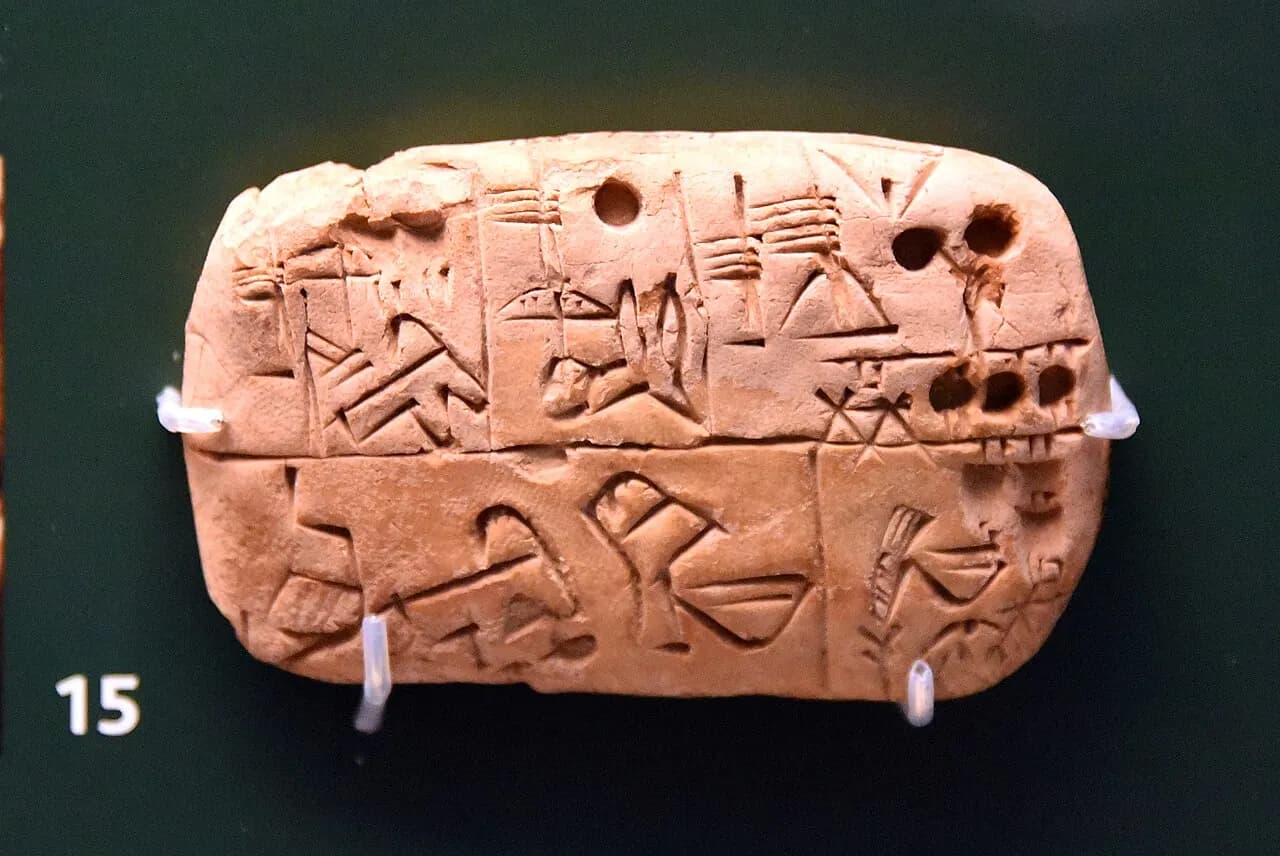
About 5,000 years ago, in Uruk, in what is now southern Iraq, a scribe pressed signs into clay: about 135,000 liters of barley delivered over 37 months to a temple brewery. Next to it, a sign read as Kushim. It may have been a man, or it may have been a job title. One of the oldest names known to humanity appears on a receipt.
In a city of tens of thousands, nobody can keep track in their head of who brought what to the granary. A few centuries earlier, the region’s accountants sealed small clay tokens inside hollow balls. To know what was inside without breaking the ball, they pressed the tokens into its surface. According to the archaeologist Denise Schmandt-Besserat, those impressions are the first signs of writing. Other specialists find that lineage too direct for the pictographic signs, but agree that the first numerical signs come from those impressions.
About 5,000 tablets from that period survive at Uruk. In the oldest layer, fewer than one in a hundred is about anything other than accounts: rations of grain and beer, livestock, workers. There, before people wrote down their gods, their kings or their stories, they wrote down their debts.
The textbook story, of barter coming before money, finds no trace here. In 1985 the anthropologist Caroline Humphrey put it bluntly: “No example of a barter economy, pure and simple, has ever been described, let alone the emergence from it of money.” In Mesopotamia, goods were valued in ShekelA unit of weight, about 8.3 grams of silver, used to value goods long before coins.Read on Wikipedia without a gram of metal necessarily changing hands. People wrote down what each owed. The laws of Eshnunna and Hammurabi even set interest rates: 20% a year on silver, a third on barley. Barter shows up mostly later, where money has disappeared.
Keeping the ledger also gives the power to wipe it clean. Around 1646 BC, the Babylonian king Ammi-saduqa proclaimed an edict of justice: citizens’ debts in grain and silver were canceled, and those who had been sold for debt were freed. Erasing a line could save a family.
As long as a debt stays between neighbors, a tablet is enough. When it has to travel to someone who does not share that memory, it takes an object.
Lydia, 7th century BC: a coin, a signature
What does a coin promise?
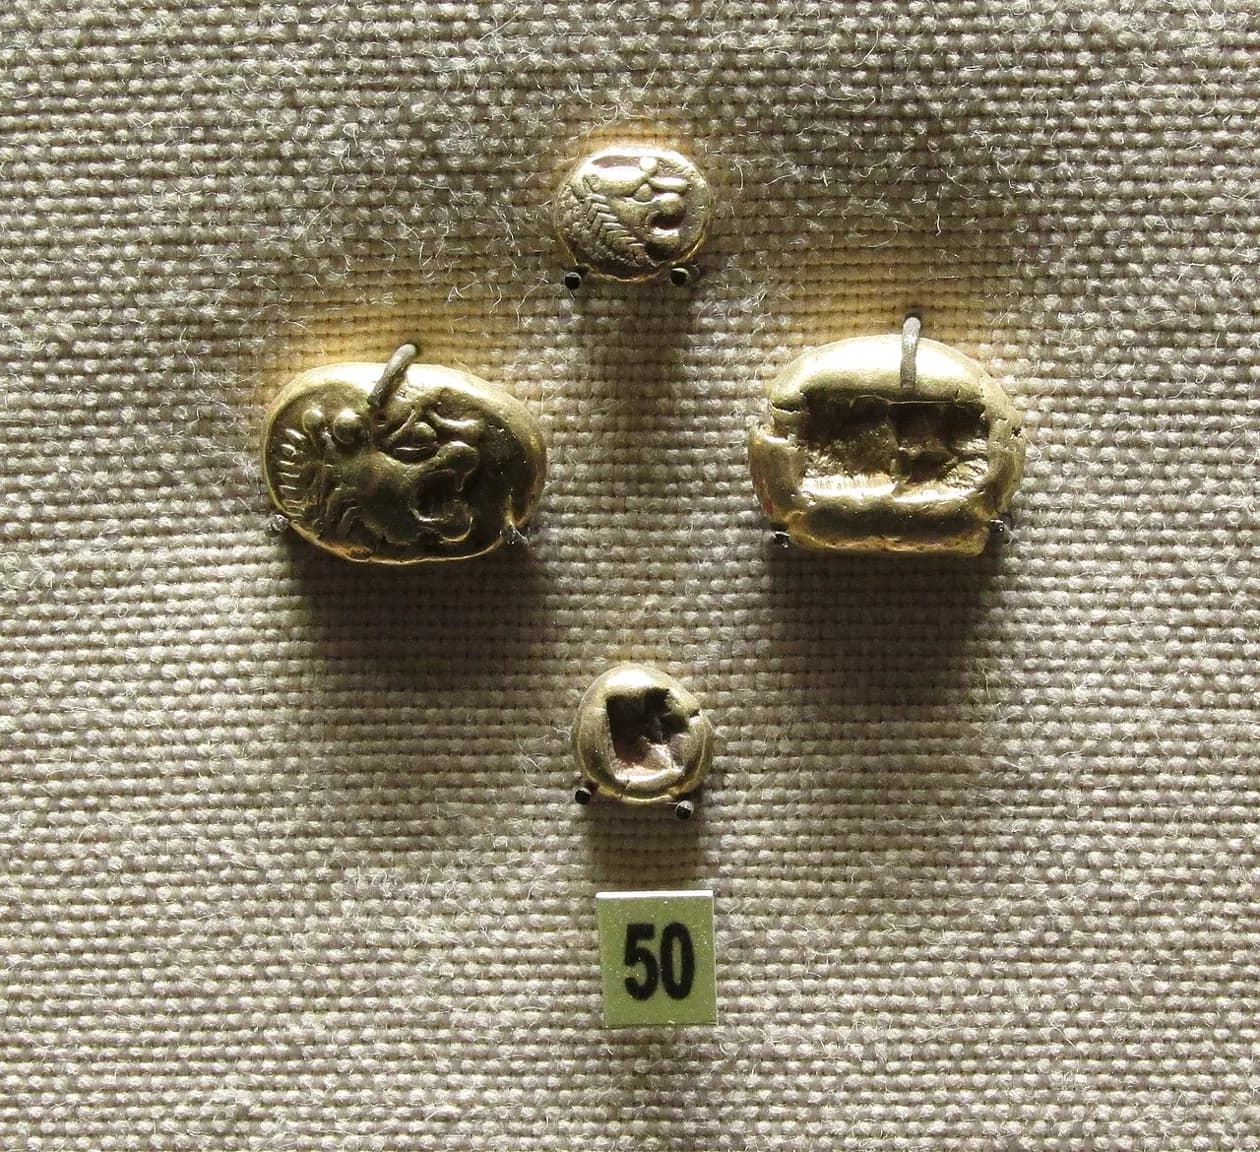
Beneath the temple of Artemis at Ephesus, archaeologists found ninety-three small lumps of ElectrumA natural alloy of gold and silver found in the rivers of Lydia.Read on Wikipedia, each stamped with a mark. They were struck toward the end of the seventh century BC, in Lydia, in what is now western Turkey.
Before that mark, a merchant had to weigh and test every piece of metal. With a coin, an issuer, often a king, vouched for the weight in advance. A stranger could accept it without scales.
That signature has a price. Whoever strikes the money takes a cut along the way, called SeigniorageThe profit an issuer makes from the gap between a money’s value and its cost of production.Read on Wikipedia. And the issuer is tempted to cheat on its own promise: put less silver in each coin, keep the face value, and pay more soldiers with the same metal.
By around AD 270, the Roman Empire’s main silver coin contained only a few percent of it, and prices soared in the years that followed. In 301 the emperor Diocletian set by edict the maximum price of more than 1,000 goods, services and wages, on pain of death for seller and buyer alike. The edict failed. Constantine restored confidence around 309 with a 4.5-gram gold coin, the solidus, whose weight would hold for more than seven centuries.
Between 1542 and 1551, Henry VIII and then his son cut the silver content of English coins from 92.5% to 25%. The Crown made about £1.3 million from it.
25%silver in English coins in 1551, down from 92.5% nine years earlier.
Cheating can also come from below. In London in 1695, the coins in circulation were missing nearly half their silver. Clippers shaved the edges of old hammered coins, spent them at face value and sold the shavings. The Crown recalled every coin in 1696 and melted it down. Isaac Newton, appointed Warden of the Mint that same year, hunted down counterfeiters and sent several to the gallows.
Inflation has often been a ruler’s decision. It can also come from elsewhere, as the cowries from Zanzibar showed. And a coin carries no farther than the signature it bears: beyond the kingdom, it took another kind of guarantee.
How do strangers come to trust each other?
- Prato, 1410: the money travels, the metal stays
- London, 2009: a £1,187 toaster
- POW camps, World War II: paying in cigarettes
Prato, 1410: the money travels, the metal stays
How does trust travel beyond the village?
When the merchant Francesco Datini died in Prato, near Florence, in 1410, he left about 150,000 documents, almost all of them business letters. Carrying coins along a road in medieval Europe meant risking your life. So Italian merchants sent something else on the road: the Bill of exchangeA written order to pay a sum in another city or on another date, which merchants could pass on.Read on Wikipedia. A merchant in Florence handed money to a banker and received a letter, which he sent to his agent in Bruges. A few weeks later, the banker’s correspondent paid that agent in Flemish money, at the agreed rate. The metal stayed put. Only the information traveled.
When metal gets too heavy, paper wins. In the seventeenth century, Sweden struck copper money whose largest plate, worth 10 daler, weighed nearly 20 kilograms. It was in Stockholm that a bank, Stockholms Banco, issued Europe’s first banknotes, in 1661.
Across much of the Muslim world and South Asia, HawalaA network of brokers who move funds between cities by extending credit to one another, without shipping cash for each transfer.Read on Wikipedia does the same thing with very little paper. You hand a sum to a broker in Dubai, and another broker pays it out to your family in Karachi. The two settle up later. In 2002 the IMF described the system as one that “depends more on absolute trust between the participants than on legal documents”.
Among friends, nobody needs letters or brokers. One pays for dinner, the other will get the next one, and each keeps a rough tally in mind. The vagueness protects, too: paying someone back to the cent can be a way of saying you are done with each other. That tally only works between people who keep seeing each other.
In 1998 the economist Narayana Kocherlakota published a paper whose title offers a key to this essay: “Money Is Memory”. He showed that, in his model, anything an economy achieves with money, it could achieve with a complete record of everything each person had given and received. That record does not exist. Money stands in for it. The stranger who takes your coin does not need to know your past, or how you came by the coin: all that matters is that others will take it in turn.
This is a different kind of trust. You do not trust your bank the way you trust a friend: you trust a system you cannot see. In October 1871, Western Union began wiring money by telegraph between New York, Chicago and Boston. In 1973, 239 banks from 15 countries founded SWIFT, a messaging network for their international payments, which now links more than 11,000 institutions. Your wire transfer is a message: an entry in one ledger, confirmed by another. These messages do more than let you pay strangers. They let you build things with them.
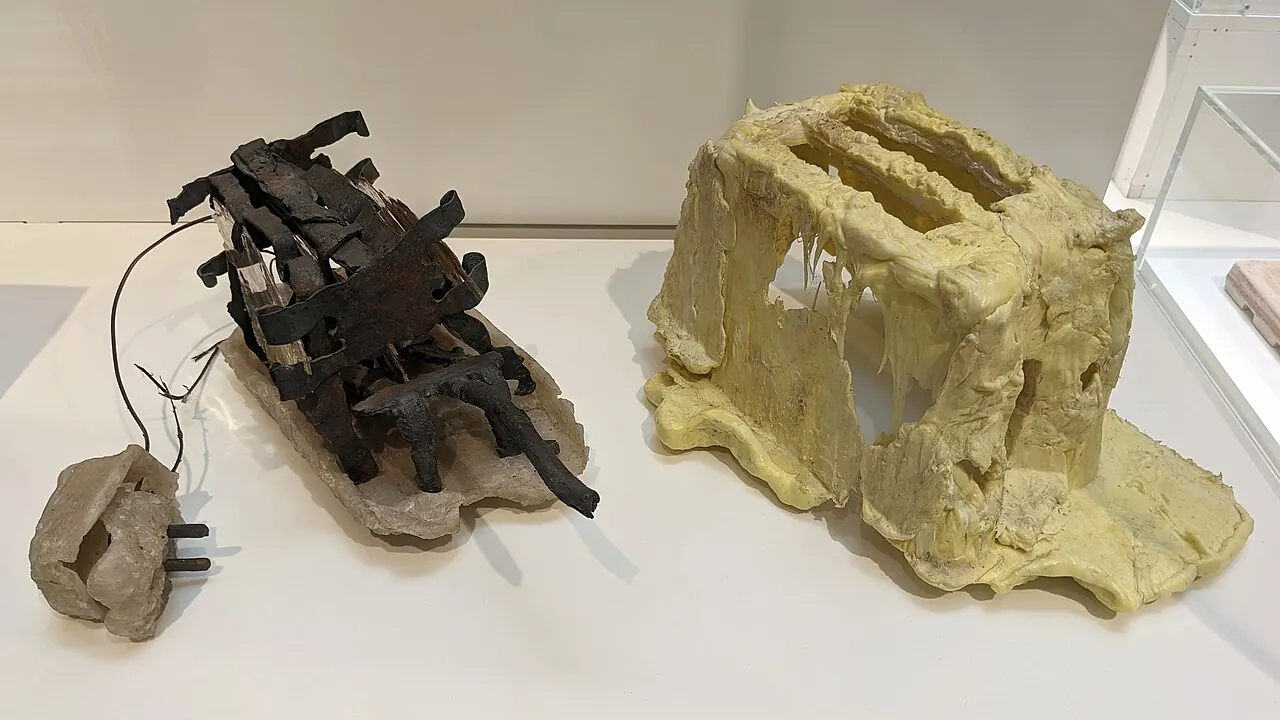
London, 2009: a £1,187 toaster
Why can’t anyone make a toaster alone?
In 2009 a student at the Royal College of Art in London, Thomas Thwaites, bought the cheapest toaster he could find, for £3.94. He took it apart, then tried to make one from scratch. He mined ore, smelted iron, tried to produce plastic. It took him nine months and cost £1,187.54. His toaster barely worked.
What a shop sells for a few pounds, thousands of strangers made together, each knowing how to make one small part. None of them knows the whole recipe. They have never spoken. What coordinates them is prices.
In 1945 the economist Friedrich Hayek put it this way: the knowledge that runs an economy never exists anywhere in full; it is scattered among millions of people. A price sums up that knowledge in a single figure. When tin gets scarce, its price rises, and people who have no idea why start using less of it.
A phone, a chip, an airplane require the cooperation of more strangers than you will meet in your life. The chain holds as long as the money that measures it holds. When one link fails, as during the 2020 pandemic, the whole chain slows down. A price is compressed memory: it sums up what millions of people know, without any of them having to remember it.
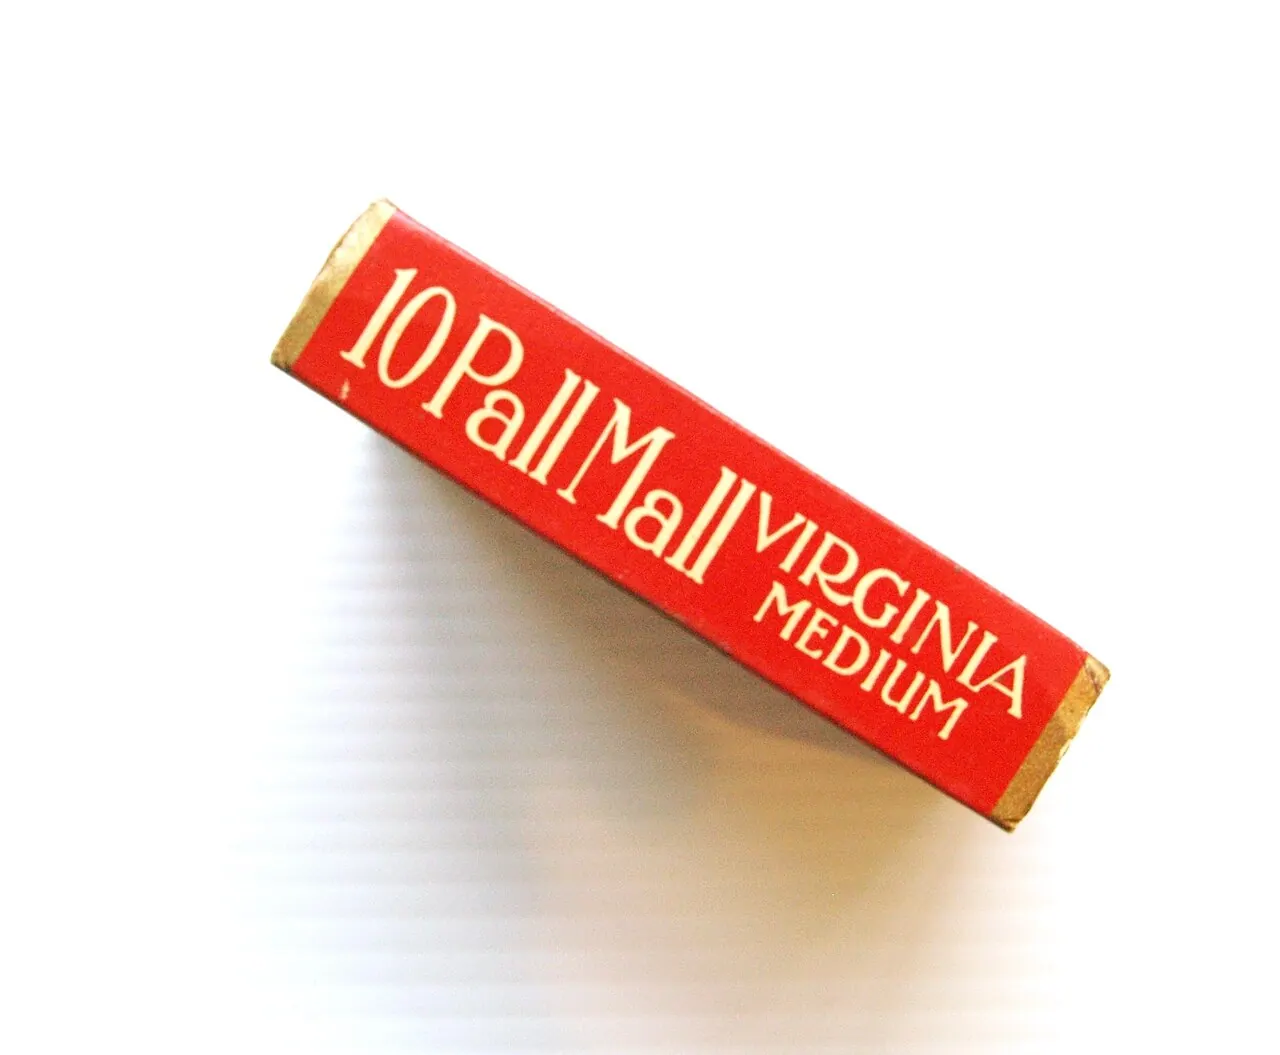
POW camps, World War II: paying in cigarettes
What is money for?
In the prisoner of war camps of Italy and Germany, cigarettes from Red Cross parcels had become the currency. Prices were set in cigarettes, and savings were kept in cigarettes. A British economist, R. A. Radford, a prisoner himself, published an account of that economy in 1945.
In a few months, the prisoners rediscovered centuries of monetary history. Some rolled cigarettes between their fingers to shake out a little tobacco before spending them, the way coins were clipped in London. Poor brands were used for paying; the best ones, such as Churchman’s No. 1, were smoked. When the Red Cross issued pipe tobacco, counted at 25 cigarettes to the ounce while an ounce made 30, everyone broke down their factory cigarettes to roll more by hand. The real cigarette vanished from the market.
Radford recognized Gresham’s lawWhen two monies must be accepted at the same value, people spend the worse one and keep the better one.Read on Wikipedia at work: when two monies are officially worth the same, people spend the worse one and keep the other. Bad money drives out good. When exchange is free, it often goes the other way: Argentines keep and use dollars.
Money does three jobs: paying (a medium of exchange), measuring prices (a unit of account) and holding value for later (a store of value). Two of those jobs pull against each other. If you think your money will be worth more tomorrow, you keep it. If you think it will be worth less, you get rid of it as fast as you can.
A money that works day to day has to be safe enough for people to accept, and not so precious that nobody spends it. That leaves the question of who sets its value. Most often, it is also whoever can take your money back.
Who can take your money back?
- Deir el-Medina, around 1157 BC: the oldest known strike
- Washington, April 5, 1933: hand over your gold
- Beirut, September 14, 2022: robbing your own bank
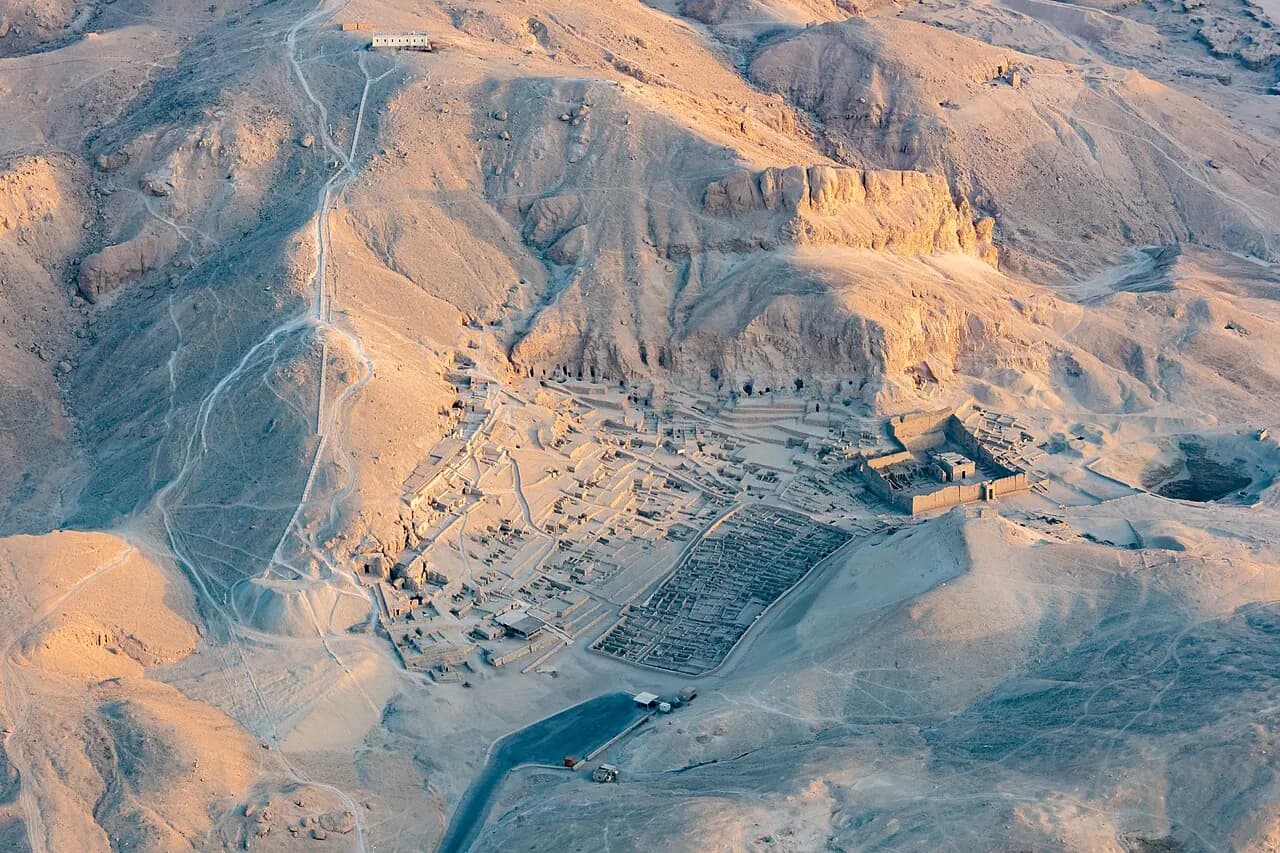
Deir el-Medina, around 1157 BC: the oldest known strike
Why are you paid in government money?
Around 1157 BC, in the twenty-ninth year of Ramesses III’s reign, the craftsmen of the village of Deir el-Medina, who dug the royal tombs, stopped receiving their grain rations. The scribe Amennakht recorded what happened next on a papyrus now kept in Turin: the crew walked past the guard posts shouting “We are hungry!” It is the oldest known strike. A SalaryThe word does not come from Roman soldiers paid in salt. Pliny the Elder links salarium to salt without ever mentioning pay in salt; the story was added by lexicographers in the eighteenth and nineteenth centuries.Read on Wikipedia was a share of the state’s stores, and a strike was a claim on its ledger.
Being paid in money rather than goods had to be won. Early in the Industrial Revolution, some British employers paid workers in tokens good only at the factory store, at prices they set themselves. In 1831 the Truck Act required wages to be paid in the coin of the realm. A paycheck in real money is the freedom to spend it somewhere other than your boss’s shop.
But why the state’s money in particular? In 1905 the German economist Georg Friedrich Knapp opened his book with one sentence: “Money is a creature of law.” For him, a money is first of all what the state accepts at its treasury, especially for taxes. In 1919 the sociologist Max Weber defined the state as a human community that successfully claims “the monopoly of the legitimate use of physical force“ within a territory. Weber, who admired Knapp, added a caveat: the law says what counts as money, but it does not decide on its own what that money is worth.
On the cowrie coast, taxes and wages had been enough. In Sierra Leone, it took a war. On January 1, 1898, the British governor of Sierra Leone, Frederic Cardew, imposed a yearly tax on every hut: five shillings, ten for the largest. In the north, the Temne chief Bai Bureh led a nine-month war, and was then exiled to the Gold Coast. In the southeast, Mende chiefs rose up as well. Ninety-six insurgents, most of them Mende, were hanged.
War played the same role as taxes. In 1672 King Charles II suspended repayment of more than £1.2 million he owed to the goldsmith bankers of London. In 1694 a new bank, the Bank of England, was founded to lend £1.2 million to the king, who was fighting France; in return, it began issuing notes. In February 1862 the US Congress authorized $150 million in inconvertible notes, the greenbacks, to pay the Union army. A state that has soldiers to pay makes money. And a state that guarantees its money can also change the guarantee.
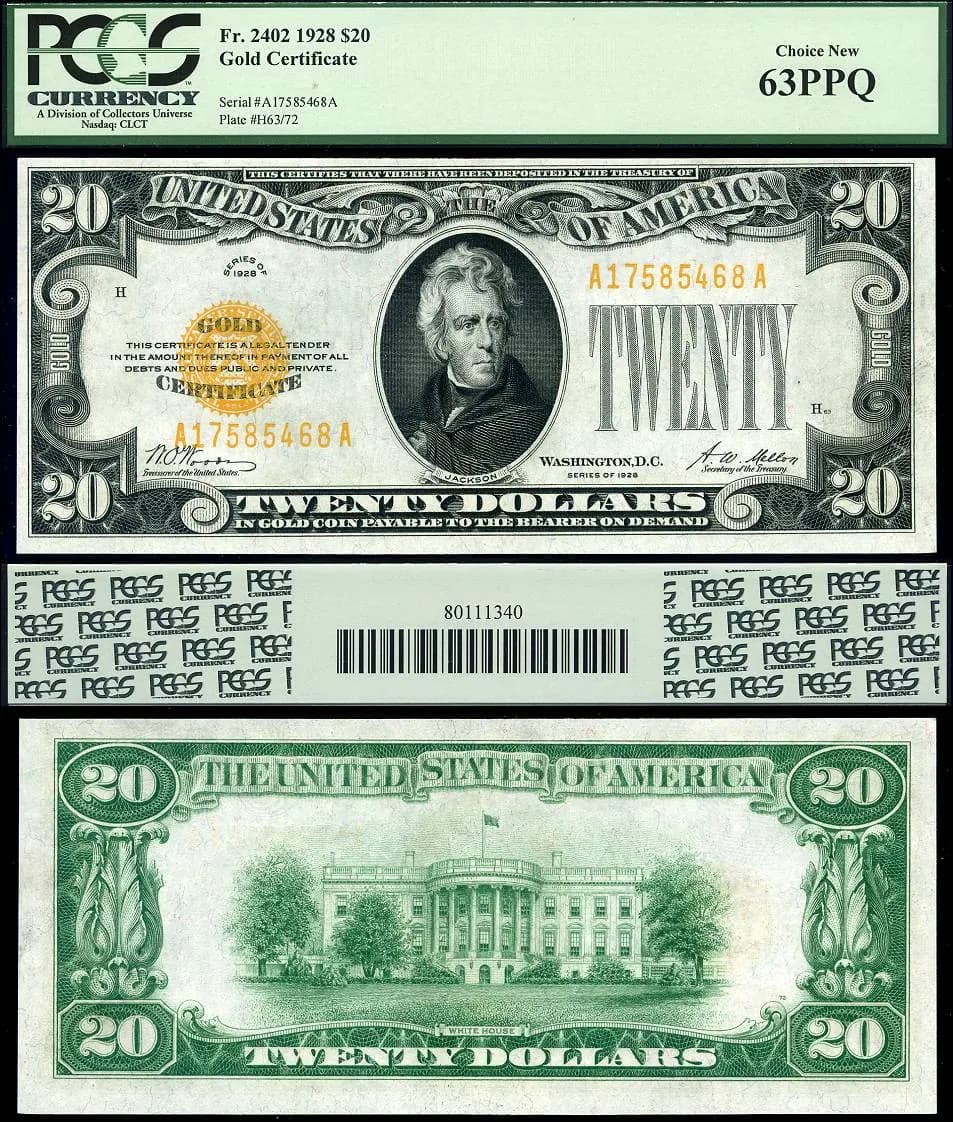
Washington, April 5, 1933: hand over your gold
What is a promise worth when its keeper changes the rules?
On April 5, 1933, President Franklin Roosevelt signed Executive Order 6102. Americans had until May 1 to hand over most of their gold coins, bullion and gold certificates to the banks, at the official price of $20.67 an ounce. Refusing could mean a $10,000 fine and ten years in prison. In January 1934 the government raised the price of an ounce to $35. The gold Americans had been forced to give up was now worth 69% more, in the government’s vaults. The goal was to devalue the dollar and push prices back up in the depths of the Great Depression, and economists link leaving gold to the recovery. For those who had believed in the rule, the state had changed it right after taking back their gold.
That rule had taken a century to set in. After the Napoleonic Wars, Britain defined its currency as a weight of gold. Germany, France and the United States followed within a few decades. A banknote became a receipt: you could exchange it for metal at the counter. Gold has what people want from a store of value: it is scarce, costly to mine, does not corrode and can be divided, and no king can create it by decree.
On December 19, 1912, the most powerful banker in America, J. P. Morgan, testified before a congressional committee. The lawyer Samuel Untermyer asked him whether credit was the basis of banking. Morgan replied: “Money is gold, and nothing else.” A few pages later in the transcript, he was asked whether commercial credit was based primarily upon money. “No, sir; the first thing is character.” Gold or trust: twenty years later, Roosevelt’s order settled it. Gold was worth something as money only as long as the state that guarded the vault did not change the rule.
In July 1944, before the war was even over, 44 countries meeting at Bretton Woods pegged their currencies to the dollar, and the dollar to gold, for foreign governments only. In 1960 the economist Robert Triffin described the trap: to supply the world with dollars, the United States had to send them abroad, and the more it sent, the less credible the gold promise became. By the early 1960s, the dollars held abroad already exceeded American gold, and the gap kept growing. On August 15, 1971, President Nixon Gold windowThe US commitment to exchange dollars held by foreign governments for gold at $35 an ounce.Read on Wikipedia. Since then the dollar has promised no metal. It promises that the American state and its economy will hold. Nobody hands in their gold today. But bank accounts still get shut.
Beirut, September 14, 2022: robbing your own bank
How can you tell a currency is about to collapse?
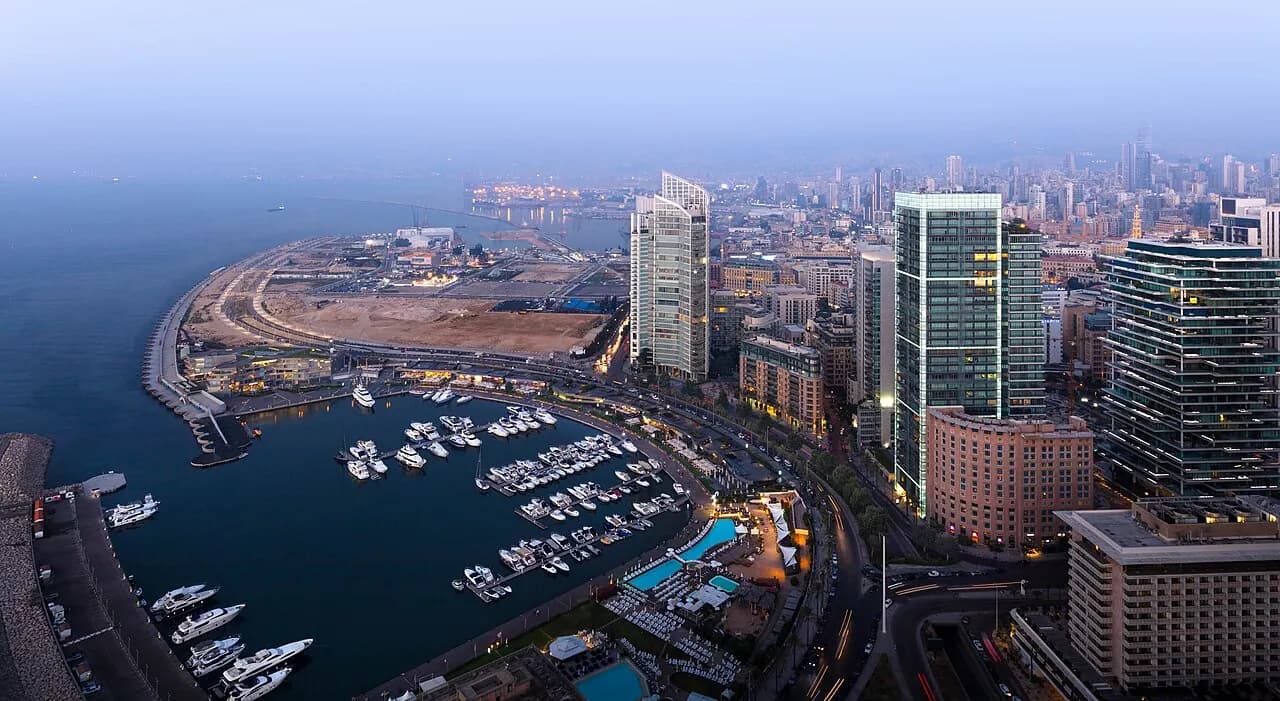
On September 14, 2022, in Beirut, Sali Hafiz walked into a branch of BLOM Bank with a pistol. She demanded the money she had deposited. Her sister had cancer, and the treatment had to be paid for. For months the bank had let her withdraw only the equivalent of $200 a month, in Lebanese pounds. She walked out with $13,000. The pistol was a toy that belonged to her nephew.
As Sali Hafiz saw it, she was only taking back what her statement said was hers. In Lebanon, since 2019, the statement and reality no longer matched. The pound had been pegged to the dollar, at 1,507.5 pounds to the dollar, for more than twenty years. By February 2023, according to the World Bank, it had lost more than 98% of its value. From 2019, the banks had restricted withdrawals without any general capital control law allowing them to. The World Bank called it “Ponzi finance”: debt piled up to create an illusion of stability and keep attracting deposits.
When a monetary promise gives way, it can give way fast. In 1923 Germany had war reparations to pay, and it financed passive resistance in the occupied Ruhr by having its central bank print marks. In October, prices doubled every 3.7 days. The crisis ended with a new currency whose issuance was capped: one rentenmark for a trillion old marks. Savers lost nearly everything.
3.7 daysthe time it took German prices to double in October 1923.
Argentina, December 1, 2001: the economy minister, Domingo Cavallo, capped withdrawals at 250 pesos a week. It came to be called the corralito, the little corral. In February 2002, dollar deposits were forcibly converted into pesos, at 1.40 pesos to the dollar, while the peso collapsed.
Cyprus, July 2013: at Bank of Cyprus, nearly half of whatever each customer held above €100,000 was forcibly turned into shares in the bank. Below that threshold, the amount was left untouched.
Lost faith shows in what people do. At the end of 2020, Argentines held about $230 billion in foreign currency outside the country’s financial system: in accounts abroad, in safe deposit boxes, under mattresses. In July 2022, a dollar on the streets of Buenos Aires cost about two and a half times its official price. In a modern bank, the run moves faster. On March 9, 2023, customers of Silicon Valley Bank pulled more than $40 billion in a single day, from their phones. With the $100 billion expected the next day, about 85% of the bank’s deposits were on their way out. In 2008 it had taken Wachovia eight days to lose $10 billion. On March 12, US authorities guaranteed all of SVB’s deposits, beyond the usual cap. The shareholders lost everything.
$40Bwithdrawn from Silicon Valley Bank in a single day, March 9, 2023.
Go deeper · 2 minOther broken promisesMexico 1982, India 2016, Nigeria 2023OpenClose
Mexico, August 1982: dollar deposits at Mexican banks, the “mexdollars”, were forcibly converted at 69.50 pesos to the dollar. When the currency market reopened on August 19, a dollar went for nearly 115 pesos. On September 1, the state nationalized the banks.
India, November 8, 2016: in a single evening, the 500 and 1,000 rupee notes were withdrawn, about 86% of the value of cash in circulation. In the end, 99.3% came back and were exchanged at banks, but cash ran short. Nigeria, February 2023: the switch to new notes turned into a shortage, and people slept outside ATMs until the Supreme Court extended the life of the old notes.
Sources: Banco de México; Reserve Bank of India, Annual Report 2017-18; Supreme Court of Nigeria (2023).
Sali Hafiz’s statement showed a sum her bank no longer wanted to hand back. In Lebanon and Argentina, depositors paid the difference. But these interventions are not alike: what sets them apart is the rules that govern that power and the recourse those rules leave you. In Cyprus, the law set the order of losses, shareholders first, then large depositors. It shielded insured deposits from any cut, without ruling out temporary limits on withdrawals. At SVB, the authorities invoked an exception written into the law to protect every depositor, and losses to the deposit insurance fund arising from the protection of uninsured deposits were to be recovered from the banks through a special assessment. The shareholders lost everything. In Lebanon, with no such law, central bank circulars regulated some withdrawals after the fact. Judges sometimes ordered repayments: in February 2023, a ruling against Fransabank set off a bank strike. Who pays depends on who keeps the ledger, on who guarantees it, and on the rules they have to follow.
Who makes money today?
- London, 2014: loans create money
- February 2022: $300 billion of Russian reserves frozen
London, 2014: loans create money
How do banks create money?
You probably picture a bank lending out its other customers’ savings. In 2014 the Bank of England wrote the opposite: “Whenever a bank makes a loan, it simultaneously creates a matching deposit in the borrower’s bank account, thereby creating new money.” Banks create most money by making loans. The Banque de France summed it up in 2024: loans make deposits.
Say you borrow $20,000 for a car. The bank checks that you can pay it back. Then it writes two entries: a loan you owe the bank, and a $20,000 deposit in your account. That deposit is new money, created on the spot. When you pay the dealer, the deposit moves to another bank, and your bank has to settle that transfer. When you repay, the loan and the money disappear together.
There are really two kinds of money. One comes from the central bank, central bank money: banknotes, and the money banks keep in their accounts with it, called reserves. The other comes from your bank: your balance. If the dealer banks where you do, your bank just moves a line. If the dealer banks elsewhere, your bank sends reserves to theirs. If it runs short, it borrows them, at a price the central bank steers with its Policy rateThe interest rate set by the central bank, which steers what banks pay to obtain reserves.Read on Wikipedia. In a crisis, the central bank lends them to sound banks: it is the lender of last resort.
In the euro area in July 2026, banknotes and coins made up just 9.2% of broad money. The rest is mostly bank deposits: economists call it deposit money, as opposed to cash, the notes and coins.
9.2%of euro area money existed as banknotes and coins in July 2026.
What stops a bank from lending without limit? Not a pile of savings. It has to make money on its loans, hold enough CapitalMoney put in by shareholders plus retained profits. It absorbs losses before customers’ deposits do.Read on Wikipedia and liquidity, find people who want to borrow, and pay the price set by the central bank. If it fails, a guarantee funded by the banks pays you back, up to a limit: $250,000 per depositor per bank in the United States, €100,000 per customer per bank in the European Union. Above that, your balance remains a promise from your bank alone.
So your balance is a promise from your bank, made credible by rules and by the state.
This setup hands enormous power to a small number of institutions: deciding, loan by loan, who gets new money first. That power has well-known abuses. When a bank belongs to an industrial group, it can lend to that group on bad terms. In Mexico in the mid-1990s, loans from banks to companies owned by their own shareholders made up 20% of commercial lending, and defaulted far more often. The economists who measured it, Rafael La Porta and his coauthors, concluded that “related lending is a manifestation of looting”. These remain abuses that the rules cap; scandals come mostly from hidden ties.
Who controls this power? Not voters, at least not directly. In the euro area, the treaty forbids the ECB from seeking or taking instructions from governments or from EU institutions. Its mandate, price stability, was set by ratified treaties, and another article bars it from financing governments directly, to avoid another Germany in 1923. It answers to the European Parliament, but the price of money for twenty-one countries is set outside the ballot box, and banks decide on their own, within the rules, whom they lend to.
Money creation also spills across borders. Outside the United States, banks lend in dollars and so create dollar deposits, beyond the Federal Reserve’s direct supervision, even though payments ultimately settle through American banks: these are EurodollarsDollar deposits held in banks outside the United States. The market grew up in London in the 1950s.Read on Wikipedia. Tax havens play a different role: they do not create money, they shelter profits. By the end of 2017, American multinationals had piled up about $1 trillion abroad, held mostly in US securities.
Go deeper · 4 minWhen a bank lends to itselfShell companies, insider loans and the rulesOpenClose
The mechanism fits in a few lines. A bank lends to a company its owners secretly control, often registered abroad. The loan creates a deposit, which leaves at once for somewhere else. The bank is left holding a claim nobody will ever repay. When the hole shows, depositors, the state or the central bank fill it.
In Ukraine, PrivatBank, the country’s largest bank, was nationalized in December 2016. The investigation by the firm Kroll, published by the central bank, describes a fraud run for at least ten years: new loans paid off old ones, and by the end of 2016, 75% of the loan book went to 36 related borrowers. The loss came to at least $5.5 billion. The state recapitalized the bank, and depositors were protected.
In Iceland, in September 2008, Kaupthing announced that a Qatari investor was buying 5% of its shares. In fact, the bank had lent the whole price, through companies in the British Virgin Islands and Cyprus: it was paying for its own shares with money it had just created. Its executives were sentenced in 2015 to four to five and a half years in prison. At Glitnir, loans to Baugur and its subsidiaries, which were tied to the main shareholders, reached about 70% of capital.
In Moldova, from November 24 to 26, 2014, Banca Sociala lent more than 13 billion lei to five companies, and the money flowed to British companies with Latvian bank accounts. Together with two other banks, about $1 billion vanished, nearly a tenth of the country’s GDP. The state took on the loss.
This is not a quirk of a few countries. In Mexico, related loans carried interest rates about 4 points lower and defaulted 33% more often. Russia’s central bank describes “captive” banks, set up by business groups to serve themselves, and revoked 51 licenses in 2017. In China, Baoshang Bank funneled 156 billion yuan to its owner through 209 shell companies between 2005 and 2019.
Rules exist. In the European Union, exposure to one client or group of connected clients is capped at 25% of Tier 1 capital, and loans to executives and their relatives must be documented for the supervisor. In the United States, loans to any single affiliate are capped at 10% of capital, and loans to insiders cannot be made on preferential terms. These rules assume you know who owns what. That is the job of beneficial ownership registers, and they have lost ground: the EU’s top court closed them to the public in 2022, and in 2025 the United States exempted its own companies.
Sources: Kroll for the National Bank of Ukraine (2017); European Court of Human Rights, Sigurður Einarsson and Others v. Iceland (2019); Kroll, Project Tenor (2015); La Porta, Lopez-de-Silanes and Zamarripa (2003); Bank of Russia (2017); Icelandic Special Investigation Commission (2010); Federal Reserve Regulations O and W; EU Capital Requirements Regulation; Court of Justice of the European Union (2022); FinCEN (2025).
At the scale of nations, creating money has a flip side: the power to freeze it.
February 2022: $300 billion of Russian reserves frozen
Why does the whole world need dollars?
In Brussels, in the accounts of the depository Euroclear, sits a large share of the Russian central bank’s reserves. In late February 2022, a few days after the invasion of Ukraine, Western countries immobilized about $300 billion of Russian reserves, most of it in Europe. In December 2025 the European Union made the freeze open-ended. In Lebanon, banks locked out their customers; here, states locked out a state that had just invaded another. The reasons have nothing in common; the mechanism does: whoever keeps the ledger decides who gets access.
$300Bof Russian central bank reserves immobilized in late February 2022.
It all comes from a simple fact: countries keep their savings with others, and mostly in dollars. More than half of central banks’ foreign exchange reserves are in dollars, and nearly nine currency trades in ten go through it. A Nigerian importer or a Korean bank lending in Jakarta needs it. In a crisis, the Federal Reserve supplies those dollars to the central banks it chooses.
In the mid-1960s the French finance minister, Valéry Giscard d’Estaing, called this America’s “exorbitant privilege“. A country whose money everyone needs borrows more cheaply, and everyone else has to earn that money before using it. After the gold window closed, Treasury Secretary John Connally reportedly told the Europeans that the dollar was “our currency, but your problem”.
The dollar is not the first to reign. In the sixteenth and seventeenth centuries, the Spanish piece of eight, struck from the silver of Potosí, circulated from the Americas all the way to China, where taxes were paid in silver. Then the pound sterling dominated the nineteenth century, before the dollar took over after 1945. The dominant currency has almost always belonged to the power that held the trade routes, and none has reigned forever.
The CFA franc shows another kind of dependence. Created in 1945, it comes in two versions, for fourteen countries in West and Central Africa. It was pegged to the French franc, then to the euro, with a guarantee from the French Treasury. In January 1994 it lost half its value overnight. In 2019 the eight West African countries won an end to depositing half their foreign exchange reserves in Paris, and France left the governing bodies of their central bank. The six Central African countries still deposit half of theirs. The fixed peg remains.
Since 2022, central banks have been buying gold at a rarely seen pace: nearly twice as much each year as in the 2010s. Many cite geopolitical risk. No other country can freeze reserves kept on a nation’s own soil. If every keeper can freeze, convert or erase, the next question is obvious: can a ledger be kept with no keeper at all?
Can memory be kept without kings or banks?
- From Kurdistan to Bitcoin: money no one can print
- Kenya, March 2007: money by phone
- From Yoruba esusu to Mexican tanda: the pot that goes around
From Kurdistan to Bitcoin: money no one can print
Can a currency with no issuer hold its value?
In the early 1990s, after the Gulf War, Iraqi Kurdistan slipped out of Baghdad’s control. Saddam Hussein had new dinars printed at will. In the north, people kept using the old notes printed before the war, known as the “Swiss” dinar because their plates had come from Switzerland. Nobody could print any more of them. No government stood behind them.
For ten years Iraq lived with two currencies. The Swiss dinar’s value tracked a bet: that the regime would fall and that new rulers would exchange it at a good rate. When Saddam fell in 2003, one Swiss dinar was worth about 300 Saddam dinars. The new authorities converted it at 150: half its peak, but above its average rate over the previous six years. For Mervyn King, then governor of the Bank of England, the lesson was clear: the value of a money depends on the survival of the institutions that define it.
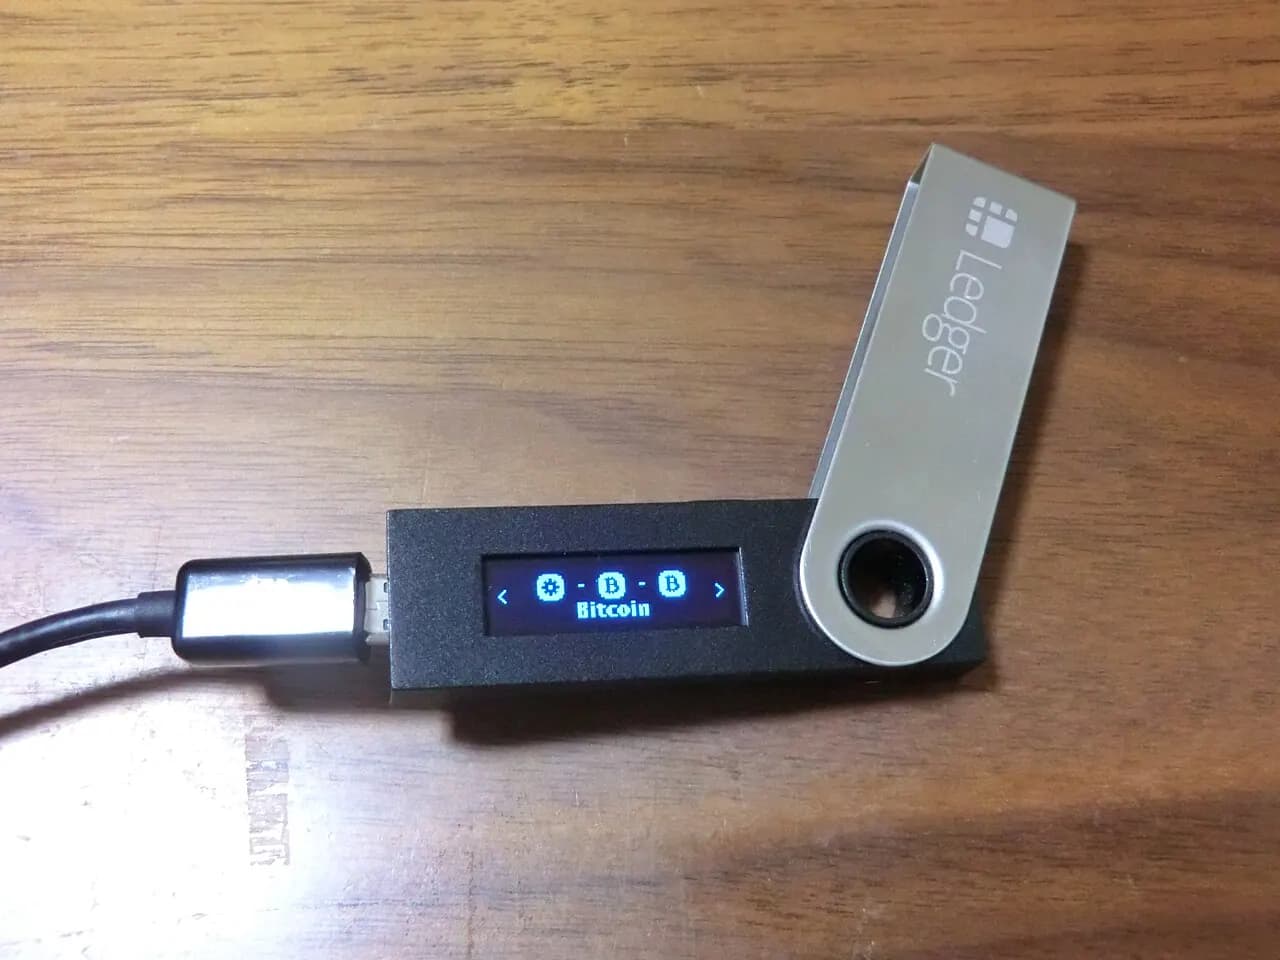
On October 31, 2008, six weeks after Lehman Brothers failed, someone signing as Satoshi Nakamoto published a nine-page paper: “Bitcoin: A Peer-to-Peer Electronic Cash System”. It promised digital payments without a “trusted third party”. The first block, mined on January 3, 2009, carries that day’s headline from The Times: “Chancellor on brink of second bailout for banks”.
Bitcoin gives its own answer to this essay’s three questions. The ledger is public, copied across thousands of computers, and anyone can check it. Nobody can decide alone to issue more: the code HalvingEvery 210,000 blocks, about every four years, the number of new bitcoins per block is cut in half. about every four years, toward a cap of 21 million. As of September 13, 2026, 95.6% of all the bitcoins that will ever exist had been created.
On May 22, 2010, a programmer named Laszlo Hanyecz paid 10,000 bitcoins for two pizzas.
$770Mthe value, on September 13, 2026, of the 10,000 bitcoins paid for two pizzas in 2010.
That is the problem: a money people expect to rise is a money they keep. When El Salvador made bitcoin legal tender in 2021, only 20% of businesses accepted it, and about 5% of their sales went through in bitcoin on Chivo, the government wallet, according to a National Bureau of Economic Research study; in 2025, accepting it became optional again. The price hit about $126,000 in October 2025, dropped toward $60,000 by February 6, 2026, less than half its record, then climbed back toward $77,000 by mid-September.
Go deeper · 3 minIs Bitcoin backed by energy?What proof of work does, and what it does notOpenClose
To add a block and receive new bitcoins, miners have to prove they performed an enormous amount of computation, paid for mostly in electricity. Satoshi Nakamoto compared this to gold miners.
More energy does not create more bitcoins. Every 2,016 blocks, the network adjusts the difficulty so that a block arrives about every ten minutes. Extra computing power buys a larger share of the new coins, not more coins.
Energy does not set the price either. Several studies, such as Ladislav Kristoufek’s in 2020, find that mining costs follow the bitcoin price, not the other way around.
The accurate claim is narrower: Bitcoin makes issuing new money costly, as gold once did. For Nick Szabo, that unforgeable cost is what makes the ledger credible. For the economist Eric Budish, it is a security bill that has to grow with the value it protects. At the end of August 2026, transaction fees made up less than 1% of miners’ revenue; the rest came from new issuance, which keeps shrinking.
Sources: Bitcoin white paper (2008); Bitcoin Core; Ladislav Kristoufek (2020); Nick Szabo (2002); Eric Budish (2025); Luxor Hashrate Index.
Bitcoin proved that a money can exist without an issuer, on rules nobody can change alone. Paying in bitcoin is possible. Making it a practical money for everyday spending is another matter. And trust comes back through another door: many holders leave their bitcoins with exchanges and funds that keep the keys for them. Nothing forces them to: whoever holds their own keys has no need to hand their bitcoins to an exchange. In November 2022, the collapse of the FTX exchange left a hole of about $8 billion in its customers’ accounts. Bitcoin removes the issuer; other digital monies only change the keeper.
Kenya, March 2007: money by phone
Who will keep the digital ledger?
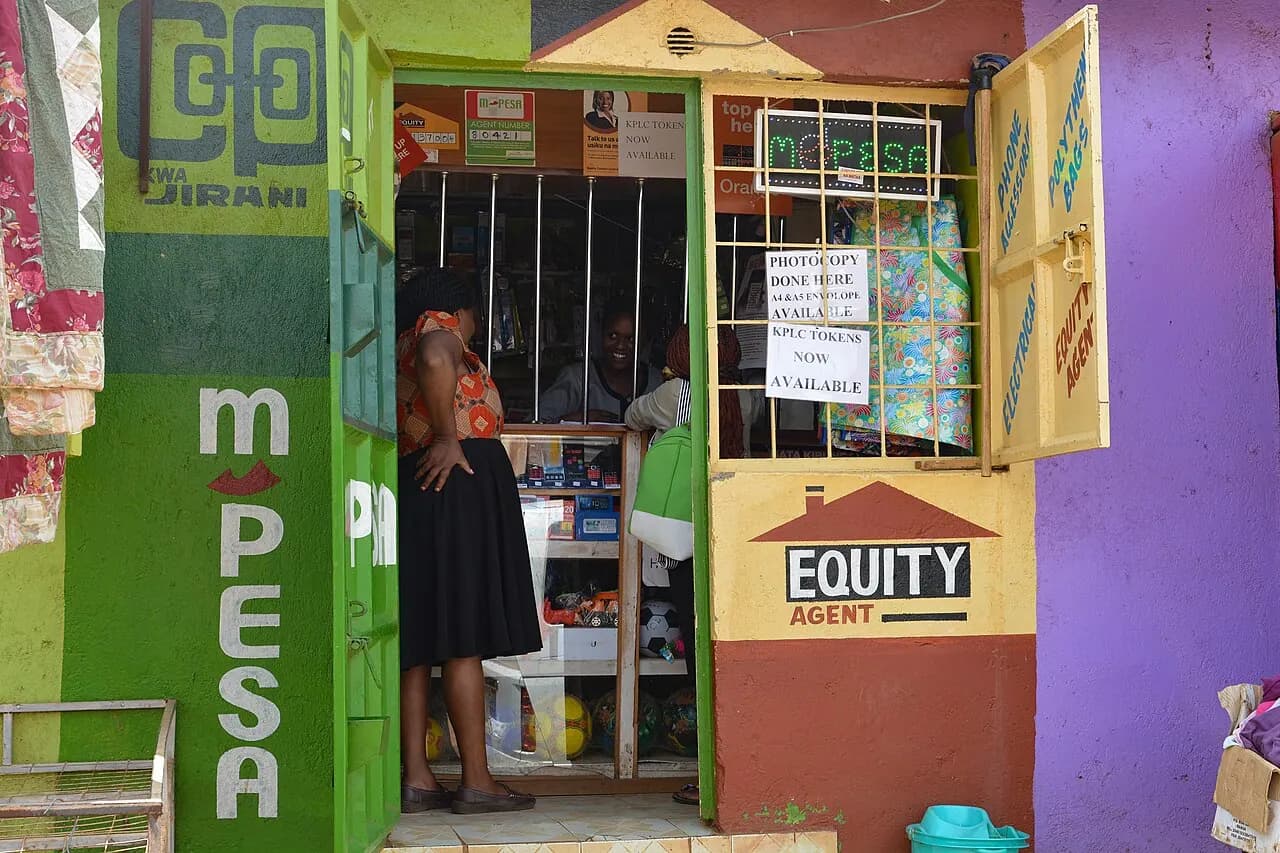
In March 2007 in Kenya, the mobile operator Safaricom launched M-Pesa: send money from a basic phone, and cash it out at a shop in the neighborhood. No bank account needed. Within a few years, millions of Kenyans were paying, saving and sending money home to their villages this way. According to a study published in Science in 2016, access to M-Pesa lifted about 194,000 Kenyan households out of poverty, 2% of the country, mostly households headed by women. Safaricom keeps the ledger, but every shilling is held in banks: M-Pesa moves money, it does not create it.
Companies now keep a large share of payment ledgers. In China, Alipay and WeChat Pay record the daily payments of hundreds of millions of people. Stablecoins go further: they are tokens that promise to be redeemed a dollar for a dollar, backed by their issuer’s reserves. At the end of June 2026, about $73 billion of USDC and about $185 billion of USDT were in circulation.
For transparency: Spliz, which publishes this blog, is an expense-sharing app for friends. It keeps expense records on its servers and lets members record repayments made elsewhere. Integrated payments and wallets were removed. A balance calculated by the app describes the group’s accounts; it is not money held in a bank account.
Central bankers recognized an old story. In 2025 the Bank for International Settlements compared stablecoins to the private banknotes of America’s free banking era. Between 1837 and 1863, more than a thousand banks issued their own dollars, and a dollar from a distant bank was worth less than its name. The United States responded with the GENIUS Act, signed into law on July 18, 2025 and taking effect no later than January 18, 2027: one dollar of safe reserves for every dollar issued, monthly reports, no lending out the reserves, no interest paid to holders. So the interest on those reserves goes to the issuer: in 2025, 96% of the $2.7 billion in revenue of Circle, the issuer of USDC, came from its reserves. And that income gets shared: in the fourth quarter of 2025, $461 million of Circle’s $770 million went back out as distribution and transaction costs, to the companies that spread USDC. The seigniorage of kings has changed hands, several times over.
Go deeper · 3 minA dollar was not a dollarAmerican banknotes before 1863OpenClose
From 1837 to 1863, a one-dollar note was the promise of one particular bank. Near that bank, it passed at face value. Farther away, merchants took it at a discount, because redeeming it meant a trip and a risk.
Merchants consulted printed guides. One Philadelphia guide lists Pennsylvania notes at par in the city, North Carolina notes at a 3.24% discount in 1839, and Indiana notes at an average discount of about 19% in 1855, some at 50%. The Office of the Comptroller of the Currency counts more than 7,000 different notes.
Most discounts were small. Across about 230,000 quotes covering 1,750 banks, the median discount was 0.5%. Steep discounts hit distant, new or shaky banks, and the economist Gary Gorton showed that markets priced those risks fairly accurately.
The Civil War ended the patchwork. From 1863, national bank notes all looked alike and were backed by federal bonds. A 10% tax on state bank notes sealed their fate: their circulation fell from $143 million in 1865 to $4 million in 1867.
Sources: Gary Gorton (1999); Gorton, Ross and Ross (2022); Federal Reserve History; Office of the Comptroller of the Currency.
States are taking the other path: central bank digital currencies would put public money directly on your phone. In May 2026, 146 countries and currency unions were exploring one, but only three had fully launched. On July 9, 2026, the European Parliament approved by 416 votes to 169 its negotiating mandate on a digital euro. The United States made the opposite choice and, in January 2025, barred its agencies from creating one. The digital euro would be issued and guaranteed by the Eurosystem; how accessible, private and secure it is would depend on the rules and safeguards chosen. This ledger could see a lot of payments: the ECB promises not to identify payers, but the law will set that limit.
Canada showed what a ledger becomes in the hands of the executive, even without a digital currency. In February 2022, the government invoked the Emergencies Act against the truckers’ convoy blocking Ottawa. An order required banks to freeze at least 257 ordinary accounts, without a judge’s decision. On January 23, 2024, the Federal Court ruled that invoking the act had been unreasonable; the Federal Court of Appeal upheld that ruling in January 2026, and the government took the case to the Supreme Court.
None of these paths makes the question go away. Each one moves the ledger, and with it the power, among a company, a state and a piece of code. That leaves a scale these three paths pass over, and one people have never done without: the group.
From Yoruba esusu to Mexican tanda: the pot that goes around
What if a group kept its own ledger?
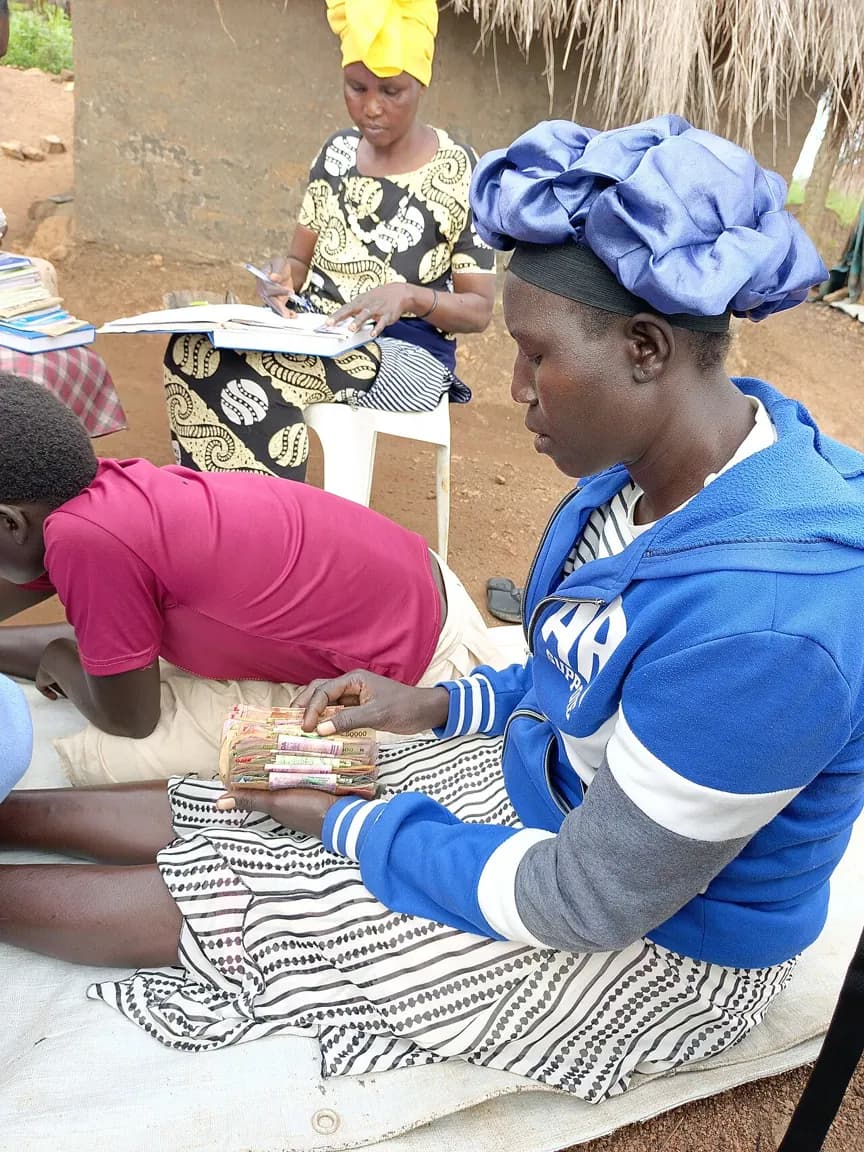
You may know how this works. Every month, in thousands of cities, a small group meets. Each member puts the same amount into a pot, and one member takes home the whole thing; the next month, it is someone else’s turn. The Yoruba call it EsusuA savings group in which each member pays a fixed sum at every meeting and receives the whole pot once, in turn.Read on Wikipedia; it is susu in Ghana and Trinidad, partner in Jamaica, tanda in Mexico, tontine in France. Africans carried off in the slave trade brought it to the Caribbean, where it lives on. These groups run without a bank or a state. Their ledger rests on reputation: whoever has collected the pot and stops paying loses their place in the group, and often beyond it. The risk is real: in Mexico, the financial consumer protection agency warns that a tanda’s organizer can run off with the money.
They protect, too. In a Nairobi neighborhood, the economists Siwan Anderson and Jean-Marie Baland found that these groups bring together mostly married women who earn their own money: joining the pot is a way for them to shield their savings from their husbands’ demands.
In 1994 the sociologist Viviana Zelizer showed that people never treat money as a neutral number. They earmark it: the vacation envelope is not the rent envelope, and the birthday check does not pay for groceries. People write those rules down however they can: an envelope, a jar, a second account. A joint account often lets either holder withdraw everything. A jointly controlled account, where every holder must agree, costs a signature for every withdrawal.
Having an account in your own name was a hard-won freedom. In France, a married woman could not open an account without her husband’s consent until the law of July 13, 1965. In the United States, before the Equal Credit Opportunity Act of October 1974, she could be refused credit in her own name. A group ledger must not erase anyone.
The political scientist Elinor Ostrom studied fisheries and irrigation canals that their users had managed for centuries. The ones that last have clear boundaries, rules decided together, monitoring by the members, graduated sanctions and a simple way to settle conflicts. A group ledger is only as good as its rules for leaving and for disagreeing. And it does not get rid of every keeper: at least it lets you know who they are.
In Kocherlakota’s model, money stands in for a complete record nobody can keep for a whole country. Among five friends, keeping a shared record of common expenses becomes possible. All it takes is writing down who paid for what, as in Uruk.
Imagine five friends renting a house for a week. Inès pays the rent, $1,500. Karim pays for the groceries, $300. Each person’s share is $360. Back home, nobody has to remember: everyone sees the same list. Karim still owes Inès $60, and the other three owe her $360 each. The ledger computes the balances, without creating money. The group decides how to settle them: to the cent, rounded off, or by letting a share go. This list has a keeper too, the app that stores it, and the three questions apply to it. Friends still fall out. But the account is written down, and every one of them can read it.
Epilogue. The lagoon and the paycheck
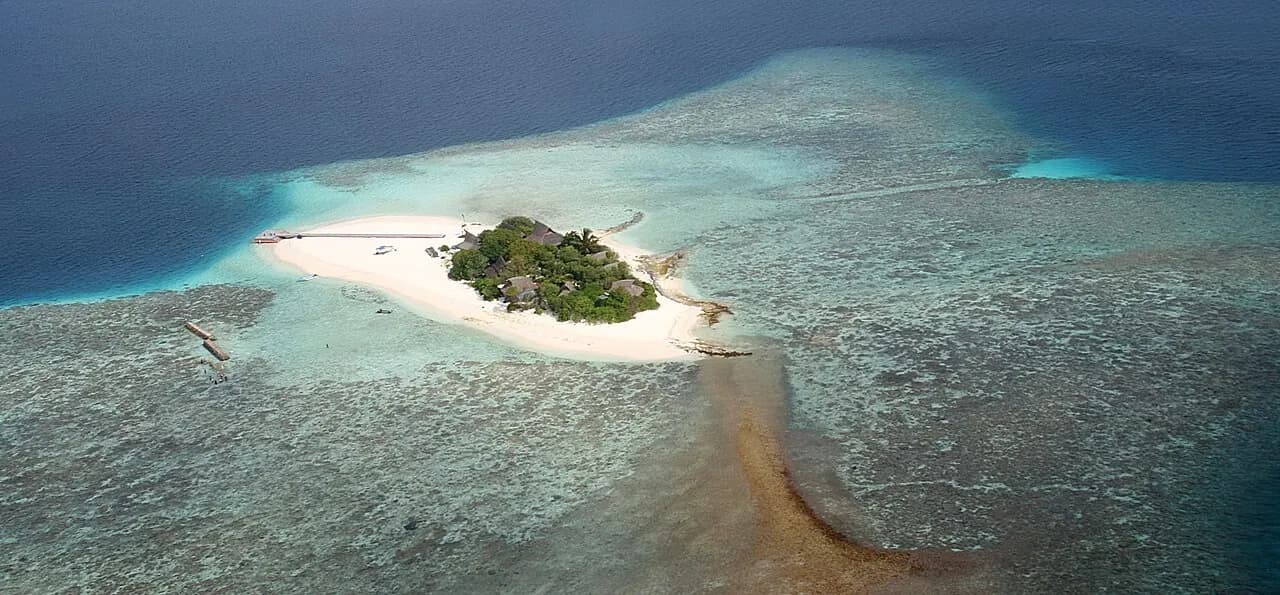
In the Maldives, cowries were traded for rice from Bengal. It was worth far more in Gao, in Ouidah, in Yunnan, because people who did not know each other believed others would accept it. It stopped being worth anything when Hamburg merchants found another lagoon, and governors decided which money taxes would be paid in.
One way to understand money is as a memory of exchanges, answering a shortage: nobody remembers everything. Sometimes a rare object stood in for memory; sometimes a keeper held it: a scribe, a king, a gold vault, a bank, a state, a piece of code. Each one protected something, and each one had its weak point.
On your next payday, the number next to your name will go up again. It is a promise, written by others. Ammi-saduqa erased debts to free families; others have frozen accounts. Before you trust a ledger, old or new, including the one you share with your friends, ask three questions. Who keeps it? Who can rewrite it? And who can erase you from it?
This essay tells a story; it is not financial advice.
Sources
- Jan Hogendorn (1981), the harvest, royal monopoly and trade of Maldivian cowries.
- Jan Hogendorn and Marion Johnson (Cambridge University Press), the shell money of the slave trade.
- Anne Haour, Annalisa Christie and Shiura Jaufar (2016), cowries in West African archaeology and the rate Ibn Battuta observed.
- Bin Yang (Routledge), cowries as the first global currency.
- Gildas Salaün, Musée Dobrée, the price of captives at Ouidah and the cargo of the Saturne.
- Leigh Gardner (2016), African monetary systems since 1800.
- Walter Ofonagoro (1979), colonial monetary policy in southern Nigeria.
- Mahir Şaul (2004), the survival of cowries in the Volta region.
- Karin Pallaver, AEHN, the currency transition in Uganda.
- Bank of Canada Museum, the stones of Yap and David O’Keefe.
- Denise Schmandt-Besserat, from tokens to writing.
- Robert Englund (CDLI), the proto-cuneiform accounts of Uruk.
- The Schøyen Collection, Kushim’s barley tablet.
- Sardis Expedition, the first coins of Lydia.
- John Munro, University of Toronto, the Great Debasement in England.
- Narayana Kocherlakota (1998), money as memory.
- IMF, Finance & Development (2002), the hawala system.
- SWIFT, the history of the network.
- Thomas Thwaites, The Toaster Project, the toaster built from scratch.
- Friedrich Hayek (1945), Econlib, the use of knowledge in society.
- R. A. Radford (1945), the economy of a prisoner of war camp.
- Museo Egizio, Turin, the strike papyrus.
- Max Weber, extract (Balliol College), the monopoly of the legitimate use of physical force.
- Bank of England Archive, the founding of the Bank of England.
- Library of Congress, the Legal Tender Act of 1862.
- Federal Reserve Bank of New York, Liberty Street Economics, the recoinage of 1696.
- FRASER, Money Trust Investigation, J. P. Morgan’s testimony.
- The American Presidency Project, Executive Order 6102.
- Steve Hanke and Nicholas Krus, Cato Institute, the hyperinflation table.
- CBS News, Sali Hafiz in Beirut.
- World Bank, Lebanon Economic Monitor, the fall of the Lebanese pound.
- Yale Journal of Financial Crises, Argentina’s corralito.
- Financial Mirror, the conversion of Bank of Cyprus deposits.
- Business Standard, India’s demonetization.
- CNN, the Nigerian Supreme Court ruling.
- Federal Reserve, Barr report (2023), the run on Silicon Valley Bank.
- World Gold Council, central bank gold purchases.
- Bank of England (2014), money creation.
- Banque de France (2024), how money is created.
- European Central Bank, monetary aggregates for July 2026.
- FDIC, deposit insurance.
- Rafael La Porta et al. (2003), related lending in Mexico.
- IMF, COFER, the currency composition of foreign exchange reserves.
- Bank for International Settlements, 2025 Triennial Survey, the foreign exchange market.
- Congressional Research Service, Russia’s immobilized reserves.
- IMF, press release 19/487, the CFA franc reform.
- Mervyn King (2004), the Swiss dinar and monetary institutions.
- Satoshi Nakamoto (2008), the Bitcoin white paper.
- National Bureau of Economic Research, Bitcoin in El Salvador.
- World Bank, Mas and Radcliffe, M-Pesa in Kenya.
- Bank for International Settlements (2025), stablecoins and money.
- US Congress, GENIUS Act, the stablecoin framework.
- Atlantic Council, CBDC Tracker, central bank digital currencies.
- CBC, the Federal Court ruling on the Emergencies Act.
- World Bank, World Development Report 1989, rotating savings groups.
- Viviana Zelizer, Princeton University Press, the social meaning of money.
- CFPB, the Equal Credit Opportunity Act.
- Toby Green, University of Chicago Press, West Africa and the money of the slave trade.
- Slavery and Remembrance, Ouidah and the kingdom of Dahomey.
- Britannica, the edict of Ammi-saduqa.
- Wikipedia, Hut Tax War, the Hut Tax War in Sierra Leone.
- Marval O’Farrell Mairal, the forced conversion of Argentine deposits in 2002.
- Federal Reserve, March 12, 2023, the guarantee of all SVB deposits.
- FGDR, deposit insurance in France.
- Direction générale du Trésor, how the franc zone works.
- Tavneet Suri and William Jack, Science (2016), M-Pesa and poverty in Kenya.
- CNN, USDC and the failure of SVB.
- CBC, the Federal Court of Appeal ruling in 2026.
- Global Informality Project, the Yoruba esusu.
- Siwan Anderson and Jean-Marie Baland (2002), savings groups in Nairobi and women’s savings.
- Ministère de l’Économie, joint and undivided accounts in France.
- Edict on Maximum Prices (Wikipedia), Diocletian’s price edict.
- Britannica, solidus, Constantine’s gold coin.
- Federal Reserve (2018), US multinationals’ cash held abroad.
- Federal Reserve Bank of Philadelphia, the succession of reserve currencies.
- Robert Triffin, Gold and the Dollar Crisis (1960), the dollar dilemma.
- World Bank (2022), Lebanon’s “Ponzi finance”.
- Banco de México, the conversion of mexdollars in 1982.
- Brookings, the Federal Reserve’s swap lines.
- Dennis Flynn and Arturo Giráldez, American silver and China.
- Sveriges Riksbank, Europe’s first banknotes.
- Circle, 2025 results, USDC reserve income.
- Condusef, the risks of tandas.
- National Bureau of Economic Research, digest, bitcoin in El Salvador.
- Backpack, the bitcoin crash of February 2026.
- Wikipedia, Bankruptcy of FTX, the collapse of FTX.
- Barry Eichengreen and Marc Flandreau, NBER, the pound and the dollar between the wars.
- EUR-Lex, TFEU article 130, the independence of the ECB.
- National Bank of Ukraine, Kroll report on PrivatBank, the PrivatBank fraud.
- European Court of Human Rights, Sigurður Einarsson and Others v. Iceland, the Al Thani case at Kaupthing.
- Kroll, Project Tenor, Moldova’s 2014 bank fraud.
- US Treasury, Federal Reserve and FDIC, joint statement of March 12, 2023, the protection of SVB depositors and how it was funded.
- Nobel Prize, Elinor Ostrom, the governance of the commons.
Friends first. Enjoy the good times.