Qivalis: the euro stablecoin of 37 banks, explained
37 banks back a euro stablecoin project. Authorization, distribution and access: the steps between a consortium and an available product.
On this page
Thirty-seven banks have joined Qivalis. As of October 10, 2026, the project’s website still states that the company is not authorized and does not provide payment services to the public. The gap between consortium strength and an available product is the starting point.
What is Qivalis?
Qivalis is an Amsterdam company, Qivalis B.V., created in September 2025 by nine European banks to issue a stablecoin pegged one for one to the euro. Under MiCA, Europe’s crypto-asset rules, such a coin is an electronic money token: issued at face value when the issuer receives your euros, redeemable at face value at any time, and forbidden from paying interest.
The application to the Dutch central bank is an announced step. The launch target remains a project timeline, not evidence of an authorization granted. Check that status again before describing the token as available.
Which banks are behind Qivalis?
The founding nine, in September 2025, were ING, UniCredit, CaixaBank, Danske Bank, KBC, SEB, DekaBank, Raiffeisen Bank International and Banca Sella. BNP Paribas joined in December, DZ BANK in January and BBVA in February, bringing the group to twelve.
Then came 20 May 2026 and twenty-five more in one announcement: ABN AMRO, Rabobank, Nordea, Swedbank, Handelsbanken, Intesa Sanpaolo, BPER, Erste Group, Crédit Mutuel, Groupe BPCE, Bank of Ireland, AIB, Bank Pekao, National Bank of Greece, Piraeus, Helaba, Jyske Bank, OP Pohjola, Landsbankinn, Spuerkeess, and five Spanish banks at once: ABANCA, Banco Sabadell, Bankinter, Cecabank and Kutxabank. The supervisory board is chaired by Sir Howard Davies, the first chairman of the UK’s Financial Services Authority. In April, Qivalis chose Fireblocks to run the token contract, the wallets and the compliance checks.
The list suggests potential distribution across countries. Ownership, product integration and convincing customers to use it are separate steps. A bank’s consortium membership does not prove its app will offer the token to every customer.
How is it different from EURC or Revolut’s EURR?
Issuer ownership is one difference: Qivalis brings banks together, while other projects pair specialized issuers with distributors. Ownership does not automatically turn a token into a bank deposit. Rights and access conditions belong in the product documents.
Who holds the reserve. MiCA requires an issuer to keep at least 30% of its reserve as deposits at banks, rising to 60% once a token is classed as significant. For a fintech that is a cost. For a consortium of banks it is home turf, and even so Sell called the 60% rule “a major financial drag” that “needs fixing”, adding that Qivalis may need up to ten treasury banks for diversification alone. The banks are building the coin and arguing against its reserve rules at the same time.
Why do banks want a euro stablecoin at all?
Because the market has already chosen the dollar. Dollar-pegged coins make up roughly 99% of stablecoin supply. The eight MiCA-compliant euro coins together were worth 673.9 million dollars at the end of June 2026, and the largest of them, EURC, had about 400 million euros in circulation in August. Sell puts the problem in one line: “In the blockchain space, the euro makes up about 0.2% of transactions.” And the consequence in another: “If there’s no usable euro, then everything just happens in dollars.”
The public alternative is slow. The European Central Bank plans a twelve-month digital euro pilot from the second half of 2027, with a possible first issuance in 2029, and only if the EU adopts the legislation this year. Qivalis wants to be live two or three years earlier, on rails the banks already understand.
Look at the use cases the consortium names, though: corporate treasury, settlement of tokenised bonds and receivables, export payments, programmable payments. Not one of them is a person paying a friend back. Sell’s own framing is that the coin “has to be available wherever the use cases are”, which so far means wholesale finance first.
Will you be able to hold it in your own wallet?
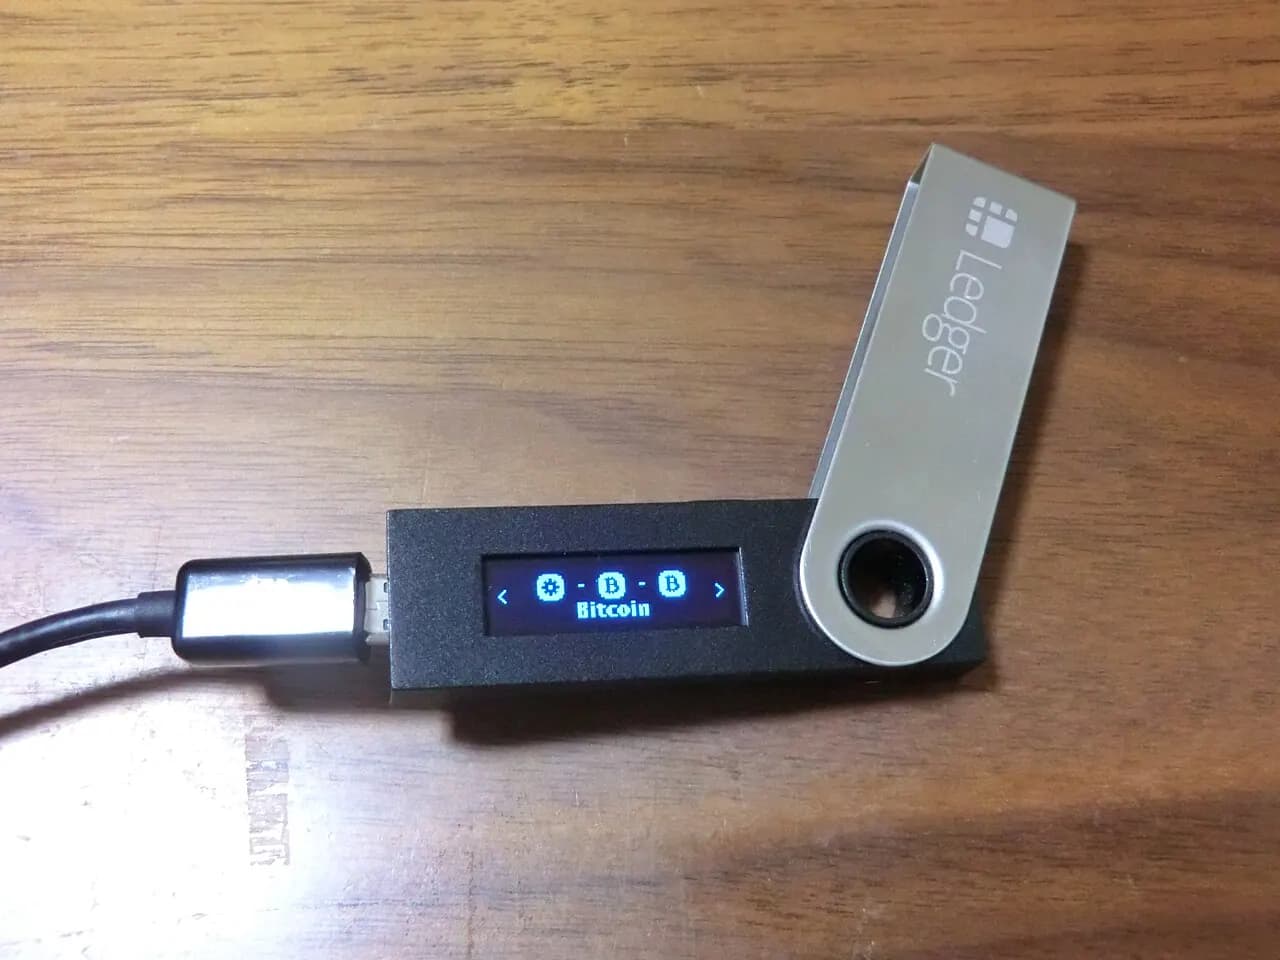
The question remains open. The following points concern the project and technical choices; they do not all represent available capabilities.
- The chain. On 8 September the crypto press reported that the coin will be issued on public Ethereum, not on a private bank ledger. Qivalis itself has published no chain list, and third-party trackers mention Polygon and Base as later steps.
- The contract. Fireblocks issues tokens under its ERC-20F standard: an ordinary ERC-20 token, plus upgradeability, plus an access list. The issuer can run it as a denylist, blocking sanctioned addresses, or as an allowlist, where only pre-approved addresses can hold or transfer the coin. Qivalis has not said which.
- The distribution. Sell has described talks with crypto exchanges and says the shareholder banks will distribute the coin themselves, once the licence lands.
A public network alone does not determine who can receive a token. Contract rules, distributor conditions and required checks also matter. Access to a ledger and access to a financial product are different things.
What would it change for splitting a bill with friends?
For a bank-issued euro coin to settle a weekend between five people, it has to clear three bars.
- An authorized, available product. An announced application is not enough to start making payments.
- Costs suited to the amount. For a $12 repayment, compare the entire journey’s fees instead of inferring a price from the network’s name.
- Recipient access. Conditions must let both people receive and use the token, including when they use different institutions.
Integrated payments were removed from Spliz. A future euro asset would need assessment across availability, receipt, cost and exit. Qivalis is not an option offered in Spliz.
What to watch next
- The DNB authorisation, and its entry on the ESMA register.
- The token’s name and ticker, which are still not public.
- A chain list published by Qivalis, not by trackers.
- The access-list policy: denylist or allowlist.
- The first member bank to put the coin in a consumer app.
The bank count explains the ambition. Access conditions and early usage will show what the project delivers.
Sources
- Qivalis, licence status wording and consortium overview.
- Qivalis press release, 20 May 2026: the 25 new members, use cases, Davies and Sell quotes.
- ING, full list of the 37 banks and the 15 countries (19 May 2026).
- Fireblocks, selected by Qivalis for tokenisation, wallets and compliance (21 April 2026).
- OpenZeppelin, audit of the Fireblocks ERC-20F standard: upgradeability and the allowlist or denylist access list.
- The Big Whale, interview with Jan-Oliver Sell (2 June 2026): reserve rules, timing, treasury banks.
- CoinDesk, Sell on the euro’s 0.2% share on-chain (31 March 2026).
- Cointelegraph, distribution through exchanges and shareholder banks, 30% deposit floor (March 2026).
- Genfinity, press report of the public Ethereum choice (8 September 2026), not confirmed by Qivalis at the time of writing.
- European Central Bank, digital euro pilot from the second half of 2027 and possible issuance in 2029.
- Decta, Euro Stablecoin Trends Report 2026: eight MiCA-compliant euro coins, 673.9 million dollars at end of June 2026.
- Circle, EURC circulation.
- EUR-Lex, Regulation (EU) 2023/1114 (MiCA): e-money tokens, redemption at face value, ban on interest, reserve rules.
Friends first. Enjoy the good times.